
Tata Elxsi · TATAELXSI
Tata Elxsi's good quarter came largely from currency; management gave no year-end margin number on the call
Sales rose 15.0% in rupees but about 8% at constant currency by our arithmetic, the margin gain was almost all exchange rates, and management declined to name a year-end margin number while saying the second half will beat the first.
Published · Inve Research Desk
21.9%
operating (EBITDA) margin last quarter
Up on the quarter before, but the chief financial officer put 60 to 70 basis points of the gain down to currency, and the margin is still below its level two quarters ago.
How they did last quarter
Sales are running ahead of the April aspiration for the full year, but about half the growth and nearly all of the margin gain came from exchange rates.
- Sales₹1,056 crore, +15.0% on a year ago; about 8% at constant currency, by our arithmeticvs April aspiration for FY27 growth: higher single digitAhead of it in rupees; the latest quarter's growth at constant currency is about 8%, one quarter set beside a full-year aspiration: about half the headline growth is currency.
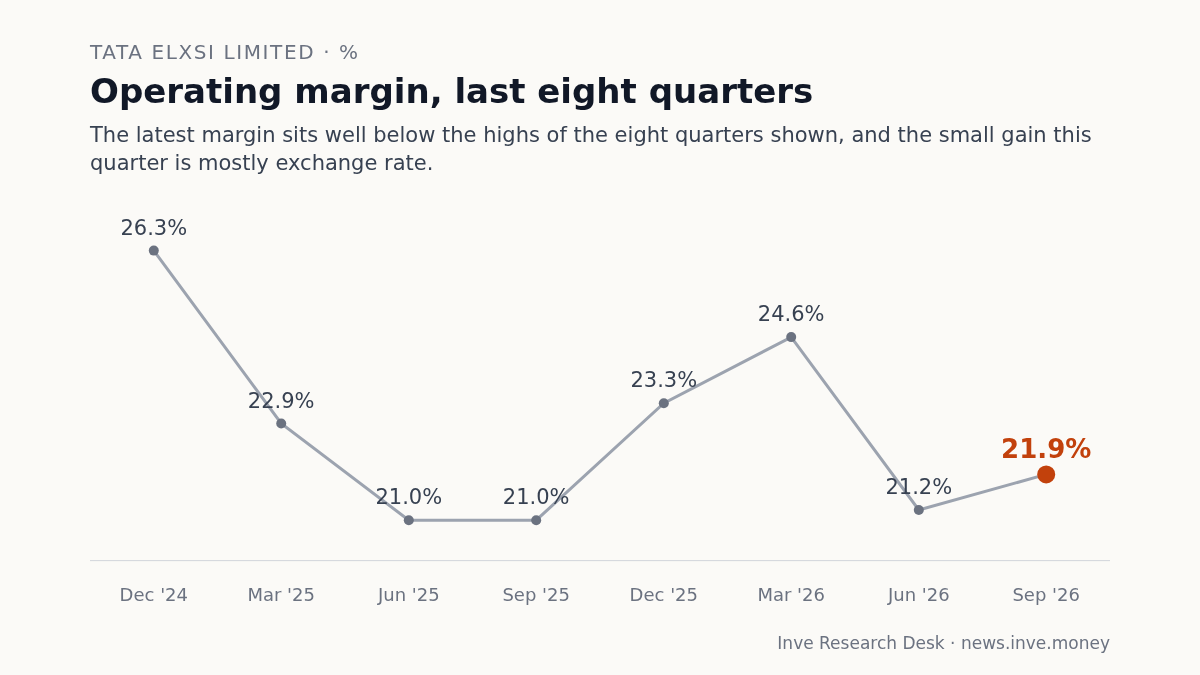
- Operating margin (EBITDA margin)21.9%, up from 21.2% the quarter beforevs 24.6% two quarters beforeA gain that currency largely explains; the margin has not regained its level of two quarters ago.
- Pre-tax margin (ours, company basis)21.9%, profit before tax as a share of sales plus other income, the company's measure, by our arithmeticvs 25.6% two quarters beforeDown over two quarters and further from the 27% mentioned in April; management gave no year-end level on this call.
The headline growth is partly currency
Tata Elxsi, which sells design and engineering services mostly to carmakers, booked sales of ₹1,056 crore in the September 2026 quarter, 15.0% more than a year earlier. That is the number a headline will use, and it is a flattering one, because exchange rates have moved. In the quarter before, the company's own growth at constant exchange rates was 6.5%, well under the rate reported in rupees.
Chaining the company's quarterly constant-currency rates forward gives about 8% for the latest quarter, by our arithmetic. Roughly half of the headline growth, then, is currency.
Sales and growth on a year ago, last eight quarters
Sales growth swung from falling to double digits within the eight quarters shown; about half of the latest growth is currency.
₹ crore; percentages in %
| Sales | Sales YoY | |
|---|---|---|
| Dec 2024 | 939 | +2.7% |
| Mar 2025 | 908 | +0.2% |
| Jun 2025 | 892 | −3.7% |
| Sept 2025 | 918 | −3.9% |
| Dec 2025 | 953 | +1.5% |
| Mar 2026 | 994 | +9.5% |
| Jun 2026 | 1,021 | +14.5% |
| Sept 2026 | 1,056 | +15.0% |
The margin gain was currency, not operations
The operating margin, which the company calls EBITDA margin and which is the share of sales left after running costs, was 21.9%, up from 21.2% the quarter before. The chief financial officer was plain about why: "about 60 to 70 bps was the cross currency benefits that we had in the quarter". A basis point is a hundredth of a percentage point, so most of a gain of under one point was exchange rate.
The rest, together with the fading of one-off costs, only covered the annual wage hike. Two quarters before, the margin had been higher.
A year-end margin goal that nobody repeated
In April Gaurav Bajaj, who spoke for the company on the April call, said the idea was, if it could, to exit the final quarter of FY27 somewhere near 27% on pre-tax margin, the company's measure. Asked this time what level it would reach by year-end, Manoj Raghavan, the chief executive, declined: "We don't want to give a number at this point in time". He said margins would improve gradually over the next two to three quarters and that the company was working out where it could get to by year-end.
By our arithmetic, on the company's measure (profit before tax as a share of sales plus other income), the pre-tax margin was 21.9% last quarter, so reaching 27% in the two quarters left would take a large step. The chief financial officer spoke of operating leverage continuing through the rest of the year, not of a jump. Operating profit is up on a year ago but still below its level seven quarters ago, on higher sales.
Operating profit and profit before tax, last eight quarters
Operating profit is below the oldest of these eight quarters despite higher sales: operating profit is about 20% above a year earlier but still below December 2024.
₹ crore
| Operating profit | PBT | |
|---|---|---|
| Dec 2024 | 247 | 256 |
| Mar 2025 | 208 | 221 |
| Jun 2025 | 187 | 196 |
| Sept 2025 | 193 | 215 |
| Dec 2025 | 222 | 146 |
| Mar 2026 | 245 | 268 |
| Jun 2026 | 216 | 232 |
| Sept 2026 | 231 | 239 |
No guidance, yet a better second half
Asked whether it would revise guidance after a first half up 14.8%, the company's strategy chief said its policy is to give none, so there is nothing to revise. Later the chief executive said the second half would be better, speaking of media and healthcare; asked to confirm, the strategy chief repeated it, and another executive said it meant revenue higher than a year earlier in the second half.
Take that at face value in rupees and the arithmetic is awkward. If the second half only matches the first, the year grows about 10.6%, by our arithmetic, which is above the higher-single-digit growth the company set out for the year in April. That reading, H2 at least equal to H1, is ours; the company did not say it on the call, and it flagged the next quarter as a short one. The latest quarter's growth at constant currency is about 8%, in line with that aspiration. Which basis management means decides whether this is a raise or a restatement, and we don't know yet which it is.
What would have to go right from here
The strategy chief said the large deals now being signed carry roughly flat margins, so the repair has to come from inside: utilisation, the share of staff time billed to clients, and reshaping the pyramid of senior and junior staff. Utilisation was up last quarter on the quarter before but short of the company's earlier peak. The chief executive called the pyramid work careful and not a one-step job.
The outside risks are specific. Several large European carmaker deals sit on the final shortlist but are unsigned, and management would not put a date on them, and JLR, a group customer, is going through layoffs, and the chief executive expects clarity across the second half. The company also flagged that the next quarter is short, with possible furloughs.
What we will watch
We will watch whether a year-end margin level comes back, whether the second half is measured in rupees or at constant rates, and whether the European deals sign. Since July 2025 the margin aim has gone from a number (the EBITDA margin), to a direction, to a number on a different measure (27% pre-tax), then no number on this call.
Companies seldom retract a number. They stop repeating it, and wait to be asked.
The record: notes, full financial tables
Notes
Impact 4/5 Margin Mixed
Tata Elxsi's 0.7-point margin gain was mostly currency, and no year-end level was given
The chief financial officer put 60 to 70 basis points of the quarter's margin gain down to cross-currency effects, and 10 to 20 to operating leverage. Operating margin (the company's EBITDA margin) was 21.9% in the September 2026 quarter, up from 21.2% the quarter before but below 24.6% two quarters before. In April Gaurav Bajaj, speaking for the company, said the idea was, if it could, to exit Q4 FY27 somewhere near 27% on pre-tax margin, the company's measure; asked on this call for a year-end level, the chief executive gave none.
“about 60 to 70 bps was the cross currency benefits that we had in the quarter”— Nalin Rana, Chief Financial Officer
Impact 4/5 Guidance Mixed
Tata Elxsi gives no guidance, yet says the second half will be better than the first
Asked about revising guidance, the company said it gives none; asked to confirm a better second half, the strategy chief agreed, and another executive said that meant higher revenue than a year earlier. Sales for the first half of FY27 were ₹2,077 crore, 14.8% above a year earlier. In April the company set out a higher-single-digit growth aspiration for FY27; by our arithmetic, a second half merely equal to the first makes the year about 10.6% up (our reading; the company did not say this on the call, and flagged a short Q3 with possible furloughs). The September quarter's growth at constant currency is nearer 8%, by our estimate.
“As a policy, and in general, we don't provide guidance at all.”— Nitin Pai, Chief Marketing and Chief Strategy Officer
Impact 3/5 Margin Mixed
Tata Elxsi doesn't expect deals alone to lift margins; it points to staff mix, utilisation
Management said the deals now being signed carry roughly flat margins, so any improvement has to come from utilisation and reshaping the staff pyramid. Utilisation was about 78% last quarter, up from 74.7% the quarter before and 73% two quarters before. Over the same stretch operating margin fell from 24.6% to 21.9%. The chief executive called the pyramid work careful and not a one-step job.
“I would not expect that there's margin improvement that is going to follow simply because you won deals now”— Nitin Pai, Chief Marketing and Chief Strategy Officer
Impact 3/5 Demand Positive
Tata Elxsi healthcare grows 3.5% at constant currency, after hopes of a Q1 recovery
Healthcare and life sciences grew 3.5% quarter on quarter at constant currency, after falling 13.1% in Q4 FY26 and 0.3% in Q1 FY27. In April management hoped the deals that slipped would let it "recover that position in Q1"; growth came in Q2 instead, and the segment is still about 10% below its Q3 FY26 level, by our arithmetic from the company's quarterly constant-currency rates. Media and communication grew 3.4% and transportation 2.0%.
“I think we bottomed out last quarter. And finally, we able to show growth.”— Manoj Raghavan, Managing Director and CEO
Impact 3/5 Risk Negative
Tata Elxsi's large European auto deals remain unsigned, with no firm date
The chief executive said Tata Elxsi is on the final shortlist for several large European carmaker deals that have not been signed, and said a timeline is very difficult to give; he said the position was not much changed from the previous quarter. Transportation grew 2.0% quarter on quarter at constant currency, with the growth coming from the US and India rather than Europe. On a group customer he described, which he went on to name as JLR, he said it is going through layoffs, with clarity expected across the second half. Transportation was 55% of revenue in the company's SDS segment in Q1 FY27.
“It could happen in this quarter. It could happen in the next quarter.”— Manoj Raghavan, Managing Director and CEO
Financials
Income statement, last 8 quarters
| Quarter end | Sales | YoY | Operating profit | Op. margin | Other income | PBT | Net profit |
|---|---|---|---|---|---|---|---|
| Sept 2026 | 1,056 | +15.0% | 231 | 21.9% | 35.0 | 239 | 170 |
| Jun 2026 | 1,021 | +14.5% | 216 | 21.2% | 41.0 | 232 | 171 |
| Mar 2026 | 994 | +9.5% | 245 | 24.6% | 51.0 | 268 | 220 |
| Dec 2025 | 953 | +1.5% | 222 | 23.3% | −50.0 | 146 | 109 |
| Sept 2025 | 918 | −3.9% | 193 | 21.0% | 49.0 | 215 | 155 |
| Jun 2025 | 892 | −3.7% | 187 | 21.0% | 38.0 | 196 | 144 |
| Mar 2025 | 908 | +0.2% | 208 | 22.9% | 43.0 | 221 | 172 |
| Dec 2024 | 939 | +2.7% | 247 | 26.3% | 40.0 | 256 | 199 |
Balance sheet
| As of | Equity | Debt | Investments | Fixed assets | CWIP | Total assets |
|---|---|---|---|---|---|---|
| Sept 2026 | 2,912 | 143 | 7.0 | 235 | 0.0 | 3,849 |
| Mar 2026 | 3,041 | 162 | 0.0 | 259 | 0.0 | 3,963 |
| Sept 2025 | 2,702 | 169 | 0.0 | 275 | 0.0 | 3,456 |
| Mar 2025 | 2,860 | 192 | 0.0 | 318 | 2.0 | 3,586 |