
Transformers and Rectifiers (India) · TARIL
TARIL's quarterly margin hits the 16% guided for the year, but plants and cash behind the next leg slip
TARIL's operating margin reached the 16% it guided, but holding its FY27 guidance needs a second half averaging more than any quarter the company has printed since June 2022, from plants whose dates keep moving, while debt has doubled.
Published · Inve Research Desk
Transformers and Rectifiers (India) stock page → More news from 14 Oct 2026
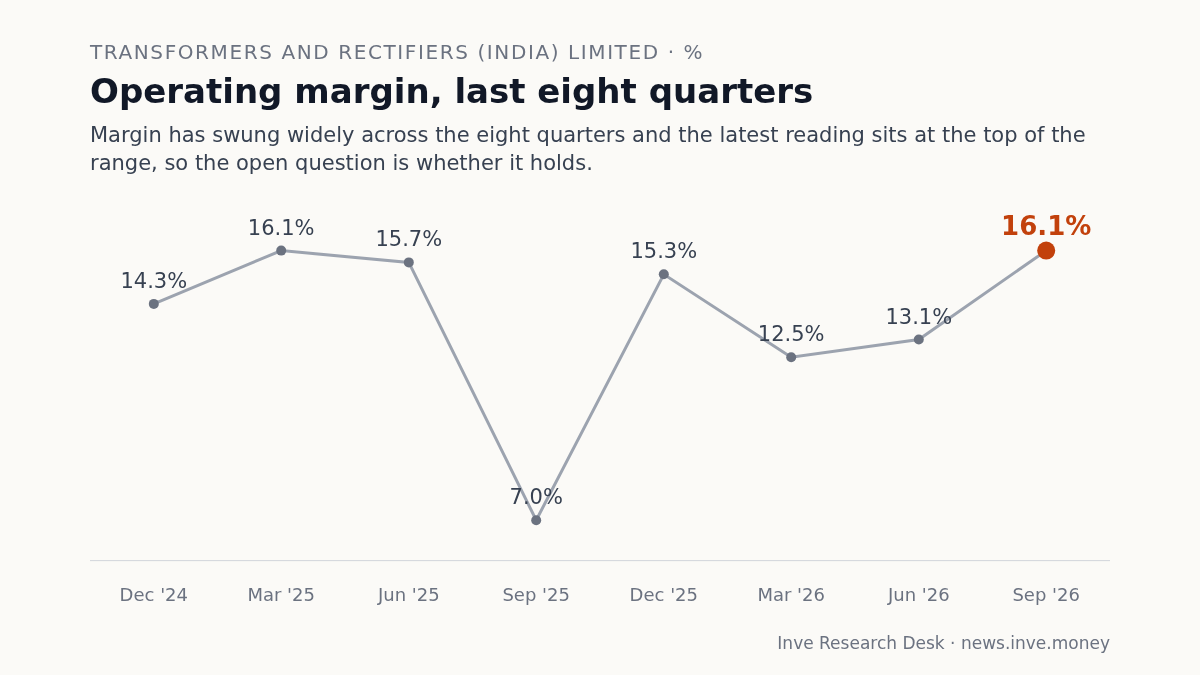
16.1%
operating margin last quarter
Level with the 16% guided for the year and up from 8.8% a year earlier as the company gave it (7.0% in our table); the second half must now hold it on far higher sales.
How they did last quarter
Margin came in at the guided level, but sales are below the best of the last eight quarters, and orders and working capital trail what management said in January.
- Operating margin16.1% (114 on 709), against 8.8% a year earlier as the company gave it (7.0% in our table)vs FY27 guidance, July 2026: "EBITDA margin of 16%"On the guided level for one quarter; the year needs about 16.9% in the second half by our arithmetic.
- Sales₹709 crore, +65.7% on a year ago, +26.8% on the quarter beforevs ₹752 crore two quarters earlier, the best of the eight shownThe jump is partly a weak year-ago base; sales are still below the best quarter.
- Order book₹7,275 crore at 30 September 2026vs January 2026 guidance for FY26-end: "around INR8,000 crores"Still short of what management guided for March 2026, six months later.
- Working capitalAbout 154 daysvs January 2026 guidance: "near to 120 days levels" by that year endBetter than about 170 at March, but well above the level guided.
Margin hit the guided 16%, and operating profit earned it
TARIL's operating margin last quarter was 16.1%. That matches the 16% the company guided for the year and is among the highest of the eight quarters in our table (the company reported 16.19% for the December 2025 quarter). A year ago the company put it at 8.8% (7.0% in our table).
Profit before tax is also now earned by the business itself. Other income, the profit that does not come from selling transformers, was a small share of profit before tax last quarter, against about a fifth the quarter before. Management credited fuller use of its Moraiya plant. This quarter's profit came from making transformers.
The guide needs a second half above the best quarter shown
On the call the CEO said the forecast is unchanged: the sales-growth guide for the year, as set out in July. That sounds like comfort, but the first half has already grown 35.0% on a year ago. Part of that is a weak base, because the year-ago quarter was depressed.
By our arithmetic, 25% on last year's sales leaves ₹863 crore a quarter for the second half. The second half must average more per quarter than any single quarter in the table; the best is ₹752 crore. The last guide ended short: in January management guided that financial year to about ₹2,600 crore of sales and a 16-17% EBITDA margin; the year printed ₹2,395 crore of standalone sales (consolidated about ₹2,509 crore, also short of that guide); on margin, the company reported 15.4% standalone EBITDA and about 17.7% consolidated, so the margin leg was met on the consolidated basis and missed on the standalone one.
Either the guide is low, as an analyst's question on the call implied, or the second-half plan is hard. Management's answers pointed both ways: the CFO said even the guide needs a little more per quarter than our figure, while the CEO said the target is that growth and beyond.
Quarterly sales, last eight quarters
No quarter shown reaches the average the full-year guide needs in the second half, which is a step above anything the company has printed.
Sales, ₹ crore
- Dec 2024 545
- Mar 2025 647
- Jun 2025 511
- Sept 2025 428
- Dec 2025 704
- Mar 2026 752
- Jun 2026 559
- Sept 2026 709
The plants meant to deliver it have moved again
In August last year management said the large Moraiya expansion would be operational within two months. By April it was to follow the monsoon. On this call the chief financial officer agreed with an analyst that the high-voltage plant is a matter for the year after this one. The CEO, Satyen Mamtora, said the work on Moraiya starts only after Changodar is done: "once we have finished this Changodar project, we start working on the Moraiya plant."
Changodar has moved too. In April it was to run from the second quarter; in July, from August; now commercial production is due around Diwali, which is the company's word and not a date. The in-house CTC (copper conductor) plant was targeted on the July call for commissioning by the second quarter of that financial year; the CEO now says commissioning in November, first trial in December and commercial manufacturing by the fourth quarter. The low end of the margin gain guided for the whole backward-integration programme was cut by half.
Debt has doubled while the plants wait
Borrowings were ₹545 crore at the end of September, more than double the level a year and a half earlier. Plants under construction, shown as capital work in progress, nearly doubled in six months.
Working capital, the money tied up in stock and unpaid bills, was still high last quarter. In January management said it should be near 120 days by March; the company then reported a figure that was still high. The goal of being net debt free within about two years, stated in August last year and again in January, was not mentioned on this call.
Debt and capital work in progress
Both rose at every date shown: borrowings and plants under construction have grown together, and the company lists debt among the ways it will pay for the plants.
₹ crore
| Debt | CWIP | |
|---|---|---|
| Mar 2025 | 260 | 62 |
| Sept 2025 | 366 | 93 |
| Mar 2026 | 424 | 138 |
| Sept 2026 | 545 | 266 |
What would have to be true, and what we do not know yet
For the guide to hold, Changodar must start producing around Diwali, and the second half must clear the quarterly bar set out above at a margin near the level just reached. Raw material costs must keep passing through to customers, and the company said supply of some critical materials is still an issue. On the July call the company said the backward-integration plants are to be paid for from QIP proceeds, leasing, internal accruals and debt if required. On this call the CFO called the funding well planned and gave no figure for the QIP money left.
Demand is not the obstacle. Unexecuted orders were ₹7,275 crore at the end of September, though in January the company had guided to a higher figure by March. The orders are there; the plants that convert them are what is in question.
We do not know yet whether the second half will reach those quarters. The next quarterly result will show how far Changodar has come. Meanwhile the debt grew.
Transformers and Rectifiers (India) stock page →
The record: notes, full financial tables
Notes
Impact 4/5 Capex Negative
TARIL puts Moraiya expansion behind Changodar, now due around Diwali
The company said commercial production at its Changodar plant should start around Diwali, and that the 22,000 MVA high-voltage expansion at Moraiya begins only once Changodar is finished. Capital work in progress, the balance-sheet line for plants still being built, nearly doubled in six months, from ₹138 crore on 31 March 2026 to ₹266 crore on 30 September 2026. On 1 August 2025 management had said Moraiya would be operational by the end of the second quarter of FY26. The chief financial officer agreed with an analyst that the high-voltage plant is a matter of FY28 onwards.
“once we have finished this Changodar project, we start working on the Moraiya plant.”— Satyen Mamtora, Managing Director and CEO
Impact 4/5 Guidance Mixed
TARIL keeps 25% FY27 growth guidance; second half needs ₹863 cr a quarter
The CEO said the forecast is the same as the July guidance of 25% sales growth, a 16% EBITDA margin and 9-10% PAT margin for FY27. By our arithmetic, 25% on FY26's ₹2,395 crore leaves ₹1,726 crore for the second half, or ₹863 crore a quarter, against a best quarter of ₹752 crore in the eight shown. In April it guided about ₹3,250 crore, 35-40% growth; the July 25% is about ₹2,994 crore on standalone FY26 sales by our arithmetic, though the CEO said on this call the INR 3,200 crore figure is maintained, which would need about ₹966 crore a quarter in the second half by our arithmetic.
“even if we go by our guidance, et cetera, we are still need to execute around INR 900-odd crores every quarter going forward.”— Mehul Shah, Chief Financial Officer
Impact 4/5 Balance sheet Negative
TARIL borrowings reach ₹545 cr as working capital runs at 154 days
The company put working capital at about 154 days, and the chief financial officer said the cycle should shrink only toward the end of this financial year. Borrowings were ₹545 crore at 30 September 2026 (about ₹575 crore standalone, the company said on the call), against ₹260 crore at 31 March 2025. In January 2026 management said working capital should be near 120 days by March 2026; on the July call the company put it at about 170. On 1 August 2025 it spoke of being net debt free within 18 to 24 months, and on 8 January 2026 within 18 months; the goal was not mentioned on this call.
“We would like to see close to about between 110 and 120 days this year.”— Satyen Mamtora, Managing Director and CEO
Impact 4/5 Margin Negative
TARIL copper plant slips to Q3 FY27; backward-integration margin gain now 100-300 points
The company said its CTC (continuously transposed copper conductor) plant will be commissioned in November, have a trial in December and make products commercially in the fourth quarter of FY27, with outside sales from the first quarter of FY28. In July it had targeted commissioning by the second quarter of FY27 and a margin gain of 200 to 300 basis points from the backward-integration programme as a whole; that range is now 100 to 300, building into FY29. By our arithmetic, 100 basis points is about ₹28 crore a year on annualised second-quarter sales.
“We are looking at 100 basis points to 300 basis point margin expansion through this backward integration.”— Satyen Mamtora, Managing Director and CEO
Impact 3/5 Margin Positive
TARIL operating margin reaches 16.1%, level with the 16% guided for the year
The chief financial officer credited fuller use of the Moraiya plant for the margin gain. Operating margin was 16.1% in the September 2026 quarter, against 13.1% the quarter before by our table (13.3% as the company gave it) and 8.8% a year earlier as the company gave it (7.0% by our table). Profit before tax was almost all operating: other income was 3% of it, against 21% the quarter before. In July management guided to a 16% EBITDA margin for the full year FY27, so one quarter now sits on the guided level; the first half was 14.7% by our table.
“this margin expansion as well as revenue, which has come from the higher capacity utilization of the Moraiya plant.”— Mehul Shah, Chief Financial Officer
Impact 3/5 Order book Mixed
TARIL order book reaches ₹7,275 cr, short of the ₹8,000 cr guided for March 2026
Unexecuted orders were ₹7,275 crore at 30 September 2026, which the company said it can execute over the next 18 to 24 months. In January 2026 it guided to around ₹8,000 crore by March 2026; on the April call it put the March book at ₹5,000-plus crore and acknowledged the miss, so this is a partial recovery that is still short. Second-quarter order inflow was ₹1,169 crore, down 44.7% from ₹2,114 crore a quarter earlier by our arithmetic.
Financials
Income statement, last 8 quarters
| Quarter end | Sales | YoY | Operating profit | Op. margin | Other income | PBT | Net profit |
|---|---|---|---|---|---|---|---|
| Sept 2026 | 709 | +65.7% | 114 | 16.1% | 3.0 | 99.0 | 75.0 |
| Jun 2026 | 559 | +9.4% | 73 | 13.1% | 14.0 | 68.0 | 50.0 |
| Mar 2026 | 752 | +16.2% | 94 | 12.5% | 22.0 | 99.0 | 77.0 |
| Dec 2025 | 704 | +29.2% | 108 | 15.3% | 6.0 | 96.0 | 71.0 |
| Sept 2025 | 428 | −4.0% | 30 | 7.0% | 12.0 | 26.0 | 17.0 |
| Jun 2025 | 511 | +63.8% | 80 | 15.7% | 16.0 | 81.0 | 60.0 |
| Mar 2025 | 647 | +29.4% | 104 | 16.1% | 11.0 | 95.0 | 77.0 |
| Dec 2024 | 545 | +49.3% | 78 | 14.3% | 9.0 | 68.0 | 51.0 |
Balance sheet
| As of | Equity | Debt | Investments | Fixed assets | CWIP | Total assets |
|---|---|---|---|---|---|---|
| Sept 2026 | 1,562 | 545 | 192 | 154 | 266 | 2,818 |
| Mar 2026 | 1,440 | 424 | 199 | 143 | 138 | 2,502 |
| Sept 2025 | 1,345 | 366 | 204 | 245 | 93 | 2,390 |
| Mar 2025 | 1,210 | 260 | 284 | 144 | 62 | 2,049 |