Punjab National Bank · PNB
PNB's margin turns up to 2.58%; a Rs 798 crore release was matched by extra provisions
Punjab National Bank's net interest margin rose to 2.58%, operating profit has stood still for three quarters, and a Rs 798 cr provision release was absorbed by extra provisions made in the same quarter.
Published · Inve Research Desk
Punjab National Bank stock page → More news from 18 Oct 2026
2.58%
global net interest margin in the latest quarter
Up 8 bp on the quarter before but still 2 bp below a year earlier, and just under the bottom of the 2.6-2.7% the bank guided for FY27.
How they did last quarter
The margin and net interest income improved, but operating profit stood still and a provision release was offset by extra provisions the bank chose to make.
- Global net interest margin2.58%, up 8 bpvs 2.50% the quarter before and 2.60% a year earlierA genuine rebound, though 2 bp short of a year ago.
- Net interest income (bank alone)Rs 11,601 cr, +10.8% on a year agovs up 7.4% on the quarter beforeIncome grew, so the margin gain is not only the result of shedding low-yield loans.
- Operating profit (bank alone)Rs 7,532 crvs Rs 7,519 cr the quarter before and Rs 7,227 cr a year earlierFlat on the quarter: shrinking recoveries and treasury offset higher interest income.
- Net profit (bank alone)Rs 5,532 cr, +5.3% on the quartervs Rs 5,253 cr the quarter beforeOperating profit barely moved; below that line a Rs 798 cr release was offset by extra provisions the bank chose to make.
The margin has recovered from its 2.47% low of March 2026
Punjab National Bank's global net interest margin, the spread between what it earns on loans and what it pays for funds, rose to 2.58% in the quarter to 30 September 2026, 8 basis points (bp) above the quarter before.
Management has guided to a rebound before. On 18 October 2025 it said the margin would improve in the quarters that followed, and it fell instead. In May 2026 it guided to a global margin of 2.6-2.7% for the current financial year; the CEO said the bank had chosen that range rather than 2.8-2.9%. The latest reading sits just under the bottom of that range.
Cheaper funding lifted the margin; repo-rate effect to come
The bank said it raised a large block of FCNR deposits, foreign-currency deposits from non-resident Indians, and used the money to run down bulk deposits and certificates of deposit that cost more. Its domestic cost of deposits also fell on the quarter. The 25 bp repo-rate rise has already taken effect, and the CEO expects its effect on the margin in the current quarter, because loans linked to it reprice the next working day.
Part of the gain is balance-sheet reshaping. Management said it shed low-yield advances, and a margin can rise simply because the weakest assets leave. Net interest income did grow as well, on the quarter and on the year, so the margin is not rising on a shrinking income base.
Operating profit has been flat for three quarters
The bank's own operating profit, its income before provisions and tax, was Rs 7,532 cr, almost level with the quarter before. Growing net interest income has not lifted it, because two older supports are shrinking.
Core operating profit, which leaves out recoveries from written-off loans and treasury trading, rose on a year ago. What remains, recoveries and treasury together, fell on the quarter, by our subtraction of core profit from operating profit. Treasury income was Rs 753 cr after a mark-to-market loss on bonds as yields rose, below the level the bank guided in July. The CEO called the recovery target for the year challenging and now gives a range that starts below it.
Group other income and profit before tax
Group other income fell to Rs 3,524 cr from Rs 4,365 cr the quarter before while profit before tax rose; it includes fees and subsidiaries, so it is a wider measure than recoveries and treasury.
₹ crore
| Other income | PBT | |
|---|---|---|
| Dec 2024 | 3,392 | 7,055 |
| Mar 2025 | 4,776 | 6,518 |
| Jun 2025 | 5,427 | 6,973 |
| Sept 2025 | 4,171 | 6,527 |
| Dec 2025 | 5,013 | 6,440 |
| Mar 2026 | 4,080 | 7,141 |
| Jun 2026 | 4,365 | 7,108 |
| Sept 2026 | 3,524 | 7,488 |
A provision release, and extra provisions against it
Net profit for the bank on its own rose 5.3% on the quarter by our arithmetic. With operating profit almost unchanged, the gain came from below the operating line, where the provisions line was Rs 97 cr after a release of Rs 798 cr on one account. The CFO said it was a provision on an investment in one account; the call did not name the account. In the same quarter the CEO said the bank made about Rs 700 cr of extra provisions on bad loans to hold its coverage ratio, plus Rs 125 cr of floating provisions. Separately, asked about an IL&FS-linked provision, the CEO said it had been written back and that the bank had kept Rs 1,150 cr of additional provision in the standard account.
Punjab National Bank stock page →
The record: notes, full financial tables
Notes
Impact 4/5 Margin Positive
PNB's global margin rises to 2.58%, with 7-9 bp more expected after the repo hike
Punjab National Bank's global net interest margin rose to 2.58% in the quarter to 30 September 2026 from 2.50% the quarter before, and the domestic margin to 2.74% from 2.64%. In May 2026 the bank guided to a FY27 global margin of 2.6-2.7%, rather than the 2.8-2.9% the CEO said it had chosen not to give, so the 2.58% figure sits just under the bottom of that range. The CEO expects a further 7-9 bp from the 25 bp repo rate rise in the current quarter.
“I'm expecting around 7 to 9 basis point addition should further happen in this particular quarter.”— Ashok Chandra, MD and CEO
Impact 4/5 One-off Mixed
PNB's bank-alone profit rose 5.3% on the quarter with a Rs 798 cr provision release
The bank on its own earned Rs 5,532 cr (up 5.3% by our calculation) against Rs 5,253 cr the quarter before, while operating profit was Rs 7,532 cr against Rs 7,519 cr. Provisions were Rs 97 cr after Rs 798 cr was released on one account. The CEO said the same quarter carried about Rs 700 cr of extra provisions on bad loans and Rs 125 cr of floating provisions, and, asked about an IL&FS-linked provision, said it was written back and Rs 1,150 cr kept in standard-account provision. The CFO said it was a provision on an investment; the account was not named on the call.
“there is a release of INR 798 crores in one account, which was in the form of investment”— Raman Grover, CFO
Impact 4/5 Guidance Negative
PNB treasury income of Rs 753 cr falls below the Rs 900-1,000 cr it guided in July
Treasury income was Rs 753 cr in the September 2026 quarter after a mark-to-market loss on bonds as yields rose. In July 2026 the bank guided to Rs 900-1,000 cr a quarter, and in October 2025 to at least Rs 1,500 cr. The CEO now puts FY27 recoveries at Rs 12,000-13,000 cr, against Rs 13,000 cr guided in July.
“But of course, it is challenging figure, somewhere INR 12,000 crores to INR 13,000 crores will be there.”— Ashok Chandra, MD and CEO
Impact 4/5 Guidance Positive
PNB cuts expected-loss rule cost estimate on loans to Rs 8,000 cr from Rs 9,000-10,000 cr
The CEO now puts the one-time cost of the RBI's expected-loss provisioning rules, which the bank said in July take effect on 1 April 2027, at about Rs 8,000 cr on the loan book; the CEO said the effect on the held-to-maturity investment book is separate and still to be settled. In July 2026 the bank put it at Rs 9,500-10,000 cr; the CEO called the earlier figure Rs 9,000-10,000 cr. The CEO said about Rs 5,000 cr is needed against Rs 2,560 cr of floating and Rs 1,150 cr of standard-asset provisions held; by our subtraction, 8,000 less 3,710 is 4,290, and the call did not explain the difference.
“Roughly, it is going to come to around INR 8,000 crore now, on the loan book.”— Ashok Chandra, MD and CEO
Impact 3/5 Risk Mixed
PNB slippages rise to Rs 2,395 cr, with one corporate account and agriculture on watch
Fresh slippages were Rs 2,395 cr, a slippage ratio of 0.77% on the bank's measure, against Rs 2,080 cr and 0.68% the quarter before, and included a road-sector corporate account. Gross NPA fell to 2.55% from 2.78%, still 5 bp above a guide of below 2.5% for the full year FY27. The CEO said stress in drought-hit agriculture is not visible in the data but the bank is watching it.
“There is no alarm button to be pushed now.”— Ashok Chandra, MD and CEO
Financials
Income statement, last 8 quarters
| Quarter end | Sales | YoY | Other income | PBT | Net profit |
|---|---|---|---|---|---|
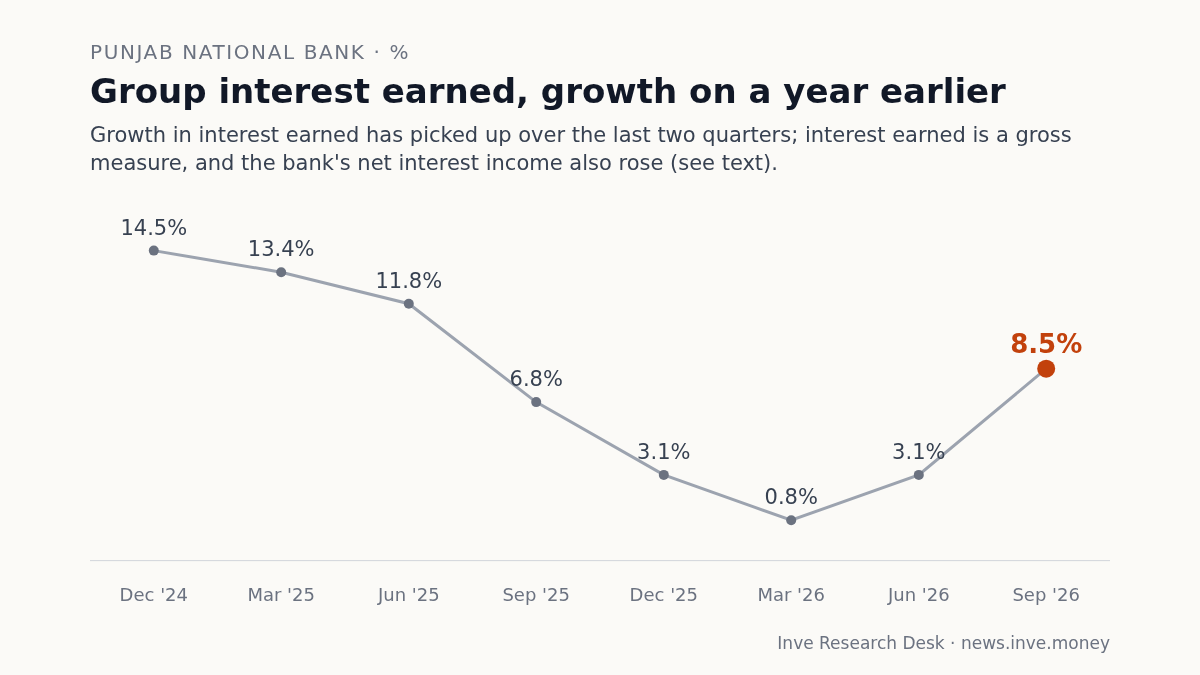
| Sept 2026 | 35,267 | +8.5% | 3,524 | 7,488 | 5,918 |
| Jun 2026 | 33,589 | +3.1% | 4,365 | 7,108 | 5,835 |
| Mar 2026 | 32,798 | +0.8% | 4,080 | 7,141 | 5,602 |
| Dec 2025 | 32,889 | +3.1% | 5,013 | 6,440 | 5,577 |
| Sept 2025 | 32,513 | +6.8% | 4,171 | 6,527 | 5,121 |
| Jun 2025 | 32,572 | +11.8% | 5,427 | 6,973 | 2,167 |
| Mar 2025 | 32,523 | +13.4% | 4,776 | 6,518 | 5,011 |
| Dec 2024 | 31,895 | +14.5% | 3,392 | 7,055 | 4,811 |
Balance sheet
| As of | Equity | Debt | Investments | Fixed assets | CWIP | Total assets |
|---|---|---|---|---|---|---|
| Sept 2026 | 1,60,982 | 1,37,836 | 5,47,217 | 15,611 | 0.0 | 21,28,852 |
| Mar 2026 | 1,49,973 | 1,07,558 | 5,23,515 | 15,625 | 0.0 | 20,33,331 |
| Sept 2025 | 1,42,247 | – | 5,31,967 | 15,624 | 0.0 | 19,20,935 |
| Mar 2025 | 1,33,138 | 1,05,807 | 5,24,840 | 13,083 | 0.0 | 18,57,544 |