
ICICI Life Insurance · ICICIPRULI
ICICI Life's 26.0% margin is largely a mix gain, and the regulator is eyeing part of that mix
ICICI Life's new-business margin rose to 26.0% on a protection-heavy mix whose growth the company says will slow, while a regulator's consultation paper proposes a significant cut to credit life commissions, a line the company says grows in step with protection.
Published · Inve Research Desk
ICICI Life Insurance stock page → More news from 14 Oct 2026
26.0%
margin on new business in the half year to September 2026
Up from 24.7% for the year to March 2026, and the company itself credits product mix, and it says protection growth will slow in the second half.
How they did last quarter
Growth in new-business value stayed strong but slowed in the second quarter, and the margin eased from the first quarter while persistency stayed below 85%.
- Value of new business₹12.83 billion, +22.3% for the half year; about +20% in the second quarter by our arithmeticvs +24.9% in the first quarterStill fast, but slower than the quarter before.
- New-business margin26.0% for the half year; about 25.5% for the second quarter by our arithmeticvs 26.7% in the first quarter and 24.7% for the year to March 2026Above last year but already easing within the half.
- 13-month persistency84.5% for the half yearvs the January aim: "we should hit 85% and above as we go through into the later part or mid part of next year"Not yet at 85%; in January the finance chief said 85% and above by the later or middle part of next year; the aim was not repeated on this call.
- Agency premium+3.3% for the half yearvs +15.1% for total annualised premium equivalent (APE), by our arithmeticThe agency channel is growing at under a quarter of the company's pace.
The margin gain is largely a mix gain, the company says
ICICI Life Insurance, the insurer that has until now carried the Prudential name, said on 13 October 2026 that the value of the new policies it wrote in the half year rose 22.3%, at a margin of 26.0%. That margin is the value of new business divided by annualised new premium: how much lifetime profit each rupee of new annual premium is expected to bring. In the previous financial year it was 24.7%.
Ask why it rose and the finance chief gives a short answer: largely product mix. Protection policies, the pure-cover kind, made up 23.4% of annualised premium equivalent (APE) against 19.3% a year earlier.
The company has already said protection growth will slow
In July the finance chief called a continuation of the first quarter's protection growth very unlikely for the second half. On the latest call he said retail protection growth should come down to more moderate levels. Asked whether a smaller protection share would pull the margin down, he replied: "Margin is just an outcome. It is VNB divided by APE."
That is true as arithmetic and silent as an answer. By our arithmetic, the second quarter alone ran at about 25.5%, against 26.7% in the first quarter. The margin has already eased within the half, though the call did not explain why, and the company gives no guidance on the second half.
The regulator's paper proposes a significant credit life cut
The insurance regulator has issued a consultation paper, not yet a draft rule, on what distribution costs. Comments are due by the end of October 2026. An analyst put the proposal as a 2% cap with no bundling; the finance chief called that hypothetical and said it was too early to call. Asked separately about the cuts, Dhiren Salian, the finance chief, said "it does propose a fairly significant cut". Credit life is cover sold alongside a loan. From his remark that it is roughly a third of protection, we put it at about 7.8% of the half year's annualised premium equivalent (APE), by our arithmetic.
Partnership business grew more than twice as fast as total APE, which rose 15.1% by our arithmetic; an analyst, not the company, called it the channel the paper would hit most. In April management said it was aware of no commission discussions beyond a data request; in July management said it expected microfinance credit life to pick up in the second half. On the call he gave no figure for the volume response or the split between ICICI Bank and other lenders.
Agency and persistency lag the headline
The agency channel is growing slowly. Agency APE rose 3.3% in the half, a fraction of the company's growth. Thirteen-month persistency, the share of policies still in force a year on, was 84.5%; in January the finance chief said the company should hit 85% and above in the later part or mid part of next year.
Cost ratios now come excluding GST, and the finance chief said the company will later have to look at the gross figure too.
Profit after tax outgrew profit before tax
Net profit rose 26.5% while profit before tax rose 16.5%. By our arithmetic the gap between the two lines narrowed from 23.5% to 17.0% of pre-tax profit, and the call did not explain it.
Net profit and pre-tax profit, last eight quarters
Net profit sat below pre-tax profit in seven of the eight quarters; March 2026 is the exception (609 against 266 crore).
₹ crore
| Net profit | PBT | |
|---|---|---|
| Dec 2024 | 326 | 411 |
| Mar 2025 | 386 | 599 |
| Jun 2025 | 302 | 392 |
| Sept 2025 | 299 | 394 |
| Dec 2025 | 390 | 502 |
| Mar 2026 | 609 | 266 |
| Jun 2026 | 386 | 470 |
| Sept 2026 | 374 | 446 |
What we do not know yet
We do not know how far the final rules will cut credit life and partnership commissions, which comes after comments close. We do not know whether protection can hold its share of annualised premium equivalent (APE) while its growth slows, and so whether the full-year margin stays above last year's. We will watch persistency, the gross cost ratio and agency growth with the next results.
A new chief executive, Siddhartha Mishra, takes over the day after the call and said the strategy is unchanged. Asked what happens to the margin if the mix moves, the company has so far said that margin is an outcome. That describes the arithmetic correctly and leaves the question open.
ICICI Life Insurance stock page →
The record: notes, full financial tables
Notes
Impact 4/5 Risk Negative
ICICI Life: regulator proposes credit life commission cut; no estimate of effect on call
The insurance regulator has published a consultation paper on distribution costs, with comments due by the end of October 2026, and the finance chief agreed it proposes a significant cut to credit life commissions. By our arithmetic credit life is about 7.8% of the half year's ₹49.34 billion of annualised premium equivalent (APE), from his remark that credit life is roughly a third of protection. In April 2026 management said it knew of no commission discussions beyond a data request. On this call the company gave no estimate of the volume or margin effect.
“it does propose a fairly significant cut.”— Dhiren Salian, CFO
Impact 4/5 Margin Mixed
ICICI Life's 26.0% margin is largely a mix effect, and protection growth is set to taper
Value of new business rose 22.3% to ₹12.83 billion in the half year to September 2026, at a margin of 26.0% against 24.7% for the year to March 2026. Protection was 23.4% of annualised premium equivalent (APE) against 19.3% a year earlier, and the finance chief said retail protection growth should taper from the 40-50% growth of recent quarters in the second half. By our arithmetic the second quarter margin was about 25.5%, below 26.7% in the first quarter. In July he had called 60%-plus protection growth in the second half very unlikely.
“Margin is just an outcome. It is VNB divided by APE.”— Dhiren Salian, CFO
Impact 3/5 Guidance Mixed
ICICI Life's 13-month persistency is 84.5%; January's 85% aim was not repeated on the call
Thirteen-month persistency, the share of policies still in force a year on, was 84.5% for the half year to September 2026, against 84.0% in the first quarter and 84.5% for the year to March 2026. On 13 January 2026 the finance chief said the company should hit 85% and above in the later part or mid part of next year; the aim was not repeated on this call. An analyst put the 25th-month ratio at 76.2% against 77.0% in June.
“So we're not seeing anything unusual there. This is in some way expected.”— Dhiren Salian, CFO
Impact 3/5 Margin Mixed
ICICI Life quotes costs ex-GST at 18.3%; the CFO says gross will be looked at too
The company quoted cost-to-premium of 18.3% for the half year to September 2026 and 11.6% for savings products, both excluding GST. An analyst noted that including GST the ratio has risen; the finance chief said the gross figure would have to be looked at too. In our record of the July call the 13.6% savings ratio carried no ex-GST label, so it cannot be set against 11.6% as a like-for-like gain. The 30 basis point fall he cites implies a year-ago base of about 18.6% (ours), against the 19.2% reported in October 2025 for that half year, so the years are not on one basis.
“we will obviously have to look at gross of GST as well.”— Dhiren Salian, CFO
Impact 3/5 Demand Mixed
ICICI Life agency APE grew 3.3% in the half year, against about 15% for the company
Agency annualised premium equivalent (APE) rose 3.3% to ₹11.02 billion in the half year to September 2026 (4.1% in the second quarter, 2.0% in the first), while by our arithmetic total APE grew 15.1%. Bancassurance rose 4.6%, with about half of it from ICICI Bank. Partnership business grew 34.1% and group business 39.2%. In April 2026 the then CEO, Anup Bagchi, said he hoped agency growth would come back sooner than the company thought.
“We'll seek to deliver sustainable growth, Nishchint. Not putting a number.”— Dhiren Salian, CFO
Impact 2/5 Risk Mixed
ICICI Life's CEO Anup Bagchi steps down; Siddhartha Mishra takes over on 14 October 2026
Anup Bagchi's term as managing director and CEO ended on 13 October 2026. The board appointed Siddhartha Mishra, until now chief operating officer, for five years from 14 October 2026, subject to approvals. The company will be renamed ICICI Life Insurance Limited.
“Our strategy remains unchanged, delivering sustainable VNB growth while balancing business growth, profitability and risk and prudence.”— Siddhartha Mishra, incoming MD and CEO
Financials
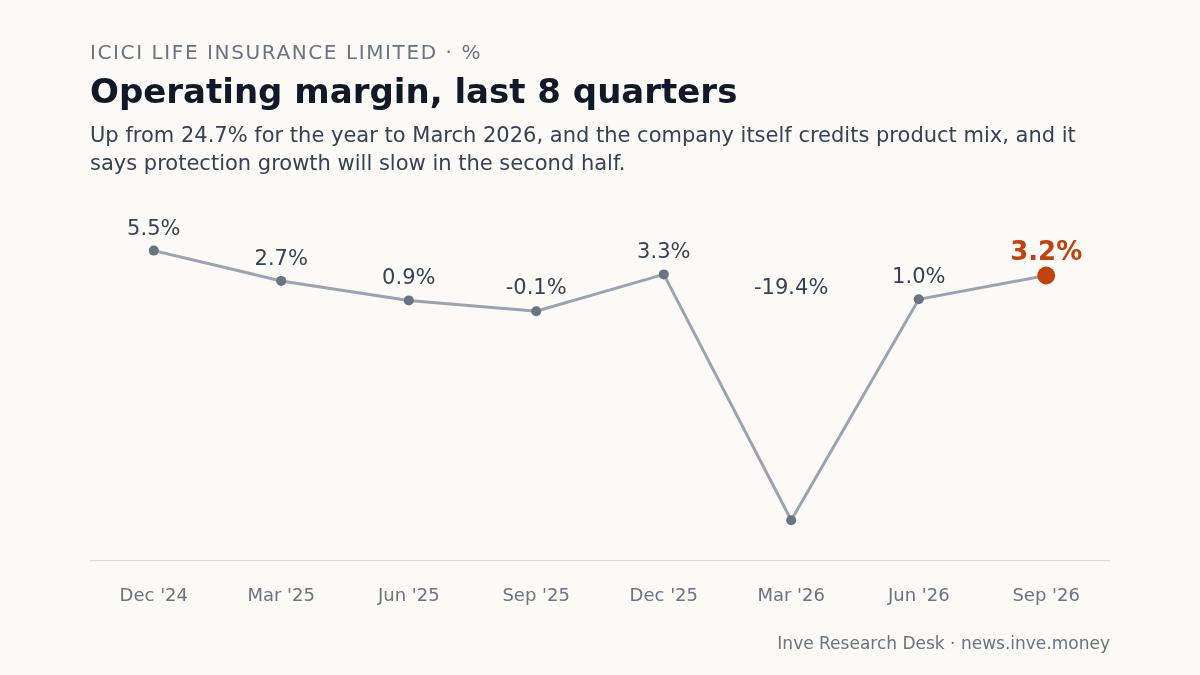
Income statement, last 8 quarters
| Quarter end | Sales | YoY | Operating profit | Op. margin | Other income | PBT | Net profit |
|---|---|---|---|---|---|---|---|
| Sept 2026 | 12,031 | +0.8% | 382 | 3.2% | 64 | 446 | 374 |
| Jun 2026 | 28,513 | +12.3% | 293 | 1.0% | 176 | 470 | 386 |
| Mar 2026 | 3,299 | −79.0% | −639 | −19.4% | 905 | 266 | 609 |
| Dec 2025 | 22,833 | +403.4% | 755 | 3.3% | −253 | 502 | 390 |
| Sept 2025 | 11,935 | −52.6% | −6 | −0.1% | 399 | 394 | 299 |
| Jun 2025 | 25,400 | 0.0% | 223 | 0.9% | 169 | 392 | 302 |
| Mar 2025 | 15,687 | −30.2% | 424 | 2.7% | 175 | 599 | 386 |
| Dec 2024 | 4,536 | −82.8% | 250 | 5.5% | 161 | 411 | 326 |
Balance sheet
| As of | Equity | Debt | Investments | Fixed assets | CWIP | Total assets |
|---|---|---|---|---|---|---|
| Sept 2026 | 14,633 | 2,595 | 3,22,543 | 715 | 0.0 | 3,32,594 |
| Mar 2026 | 15,533 | 2,595 | 3,07,369 | 1,378 | 43.0 | 3,19,735 |
| Sept 2025 | 12,715 | 2,600 | 3,15,790 | 834 | 0.0 | 3,24,512 |
| Mar 2025 | 16,343 | 2,600 | 3,03,490 | 1,314 | 35.0 | 3,14,240 |