HDFC Bank · HDFCBANK
HDFC Bank's CEO and a deputy are leaving just as its margin is said to have bottomed
The chief executive and a deputy managing director are both going, the deputy by the end of December and the chief executive on a date not stated on the call, as an analyst puts the margin at 3.32% and management names several tailwinds.
Published · Inve Research Desk
3.32%
net interest margin, as an analyst put it
Below the 3.4% to 3.5% band described in April 2025, if both are measured the same way (basis not stated on the call); management calls it the low point and names several tailwinds, led by the October repo rise.
How they did last quarter
Profit grew far more slowly than the balance sheet, and the interest bill rose for a second quarter.
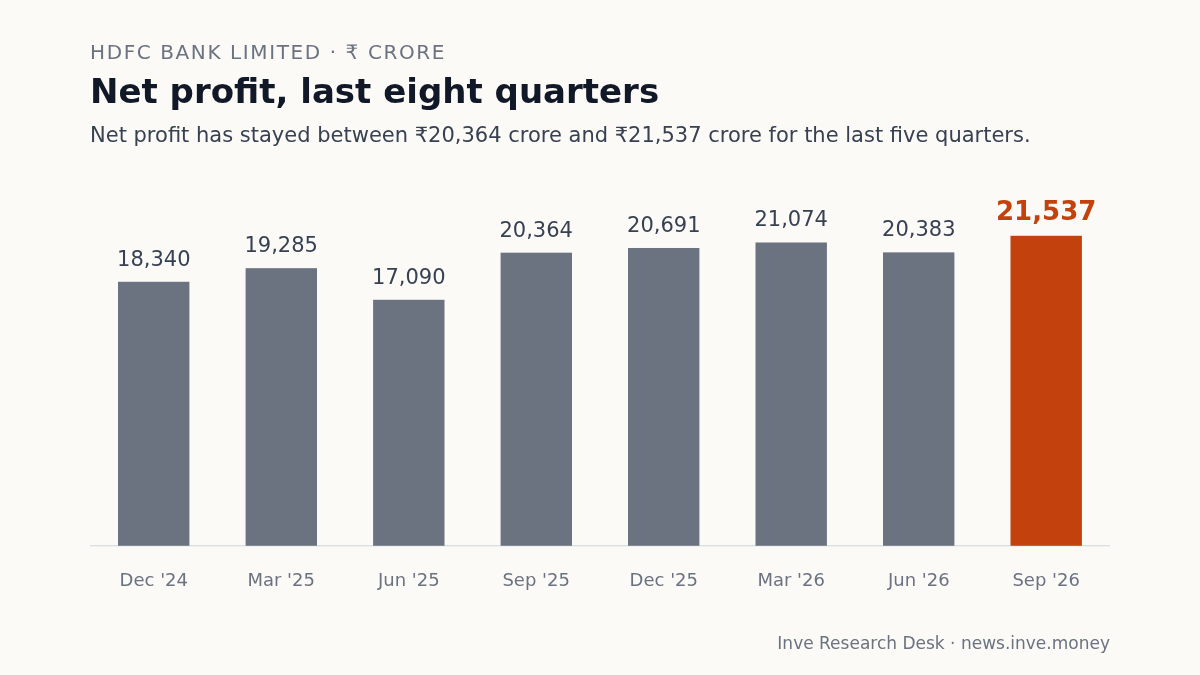
- Net profit₹21,537 crore, up 5.8% on a year agovs Total assets up 14.4% on a year ago, as filedProfit trails the balance sheet for now; the longer-term guidance is for profit growth at or above it, so this is a gap rather than a miss.
- Interest expense₹50,667 crore, up 6.4% on the quarter beforevs ₹47,626 crore the quarter beforeThe bank's funding bill rose for a second quarter, from 45,220 crore two quarters before to 47,626 the quarter before and 50,667 now.
- Deposits against loansDeposits up ₹1.57 trillion in the quarter, the CFO saidvs Loans up ₹1.58 trillion in the same quarterNew deposits roughly matched new lending; the CFO called sources and uses largely matched and agreed a level around 110-115 acts as a floor for growth.
The chief executive and a deputy are both leaving
HDFC Bank's chief executive, Sashidhar Jagdishan, used the results call to say he is leaving, and introduced a successor whom the transcript names only as Anup. Anup asked to be addressed by a title the transcript renders as 'MDS' and said he would soon present a view on growth, margins, quality and productivity; Jagdishan told analysts to expect that in about a month. At the close Jagdishan added that deputy managing director Kaizad Bharucha had asked for early retirement by the end of December. On the call, neither departure came with a stated reason (the CEO said an exchange notification on Kaizad had just gone out; we do not hold it), and the CEO's came with no effective date.
Both announcements run against earlier statements. In March, a day after the chairman resigned, the bank said the CEO's reappointment would be taken up in due course and that nothing changed after the chairman's exit, and Jagdishan said Kaizad would stay for three years. In July management called the reappointment work in progress. This call confirms the CEO is leaving, and on the call there was no account of how the reappointment ended.
Margin said to be at its low, with several tailwinds named
An analyst put the bank's net interest margin, its net interest income as a share of the assets that earn interest, at 3.32%, and the chief financial officer did not dispute it. That is under the 3.4% to 3.5% band the bank described in April 2025, if both are measured the same way; basis not stated on the call. Asked why the cost of funds looked higher, the CFO said it was flat at about 4.4%: most of the quarter's deposit increase came as time deposits, including FCNR (foreign-currency) deposits, which offset the gain from repricing older ones. Interest expense in the filed results rose 6.4% on the quarter before.
In October 2025 management expected deposit repricing to give a tailwind over the next six to twelve months. This time management's stated tailwinds are the 25 basis point repo rise in October (about 70% of loans float, and the CFO expects the rise to be largely reflected by December), back-book repricing in retail across the next two quarters, and a mix shift to retail and MSME loans; the full-quarter cost of the FCNR deposits is the offset.
The two executives put it with different strength. The CFO agreed this is the bottom and declined to give a number: "So net of that, we still think that there can be neutral to positive on the margin as we go forward." The CEO went further: "The trajectory will be upward from the next quarter onwards."
Profit growth trails the balance sheet
Net profit rose 5.8% on a year earlier in the September 2026 quarter, while total assets grew 14.4%. In July the CFO said that in the longer term profit growth should be at or above balance-sheet growth. Because the wording is longer term, the gap is not a miss. Sales less interest expense, a rough proxy for spread income that is not the bank's own net interest income, also grew more slowly than assets, calculated from the filed figures.
The CEO quoted profit growth excluding trading gains, a measure that cannot be compared directly with the filed figure. The CEO said total AUM growth of 15.3% includes 1.9 points from FCNR leverage.
Liquidity and deposit strategy go to the incoming head
The liquidity coverage ratio compares a bank's high-quality liquid assets with its expected short-term outflows. An analyst put the bank's at 113% and asked whether it limits lending; the CFO said the bank runs in a range it sets itself, and agreed that it must treat a level around there as a floor in order to lend more. Deposits and loans rose by almost the same amount in the quarter, which the CFO called largely matched. About 4 points of reported deposit growth came from the FCNR window. The CFO added that "a low LCR does not mean low liquidity".
The CFO said a strategy on deposit momentum and the balance-sheet changes needed to keep the ratio healthy would come over the next couple of quarters, and the CEO mentioned some non-deposit strategies in the restructuring; questions on deposit strategy were passed to Anup. Asset quality was steady: the gross NPA ratio was 1.11%, 13 basis points lower than a year earlier, and credit cost 44 basis points. Anup's presentation to analysts is due in about a month, and Kaizad Bharucha, who answered the loan-book questions on this call, has asked to retire by the end of December.
The record: notes, full financial tables
Notes
Impact 5/5 Risk Mixed
HDFC Bank's CEO is leaving; successor Anup to set out strategy in about a month
The chief executive said he is leaving and introduced Anup as his successor; Anup said he will soon present a view on growth, margins, quality and productivity. On 19 March, a day after the chairman resigned, the bank said the reappointment would be taken up in due course and that nothing changed; on 18 July it called the matter work in progress. The call gives no reason for the exit or a date. Anup is expected to address analysts in about a month.
“it has been an absolute privilege to lead this organization”— Sashidhar Jagdishan, MD and CEO
Impact 4/5 Risk Negative
HDFC Bank deputy MD Bharucha asks to retire early, seven months after CEO said he'd stay
Closing the call, the CEO said Bharucha has asked for early retirement by the end of December and called it a big loss to the institution. On 19 March the CEO had said Bharucha would be in the role for the next three years. The CEO called him one of the key architects of the bank's credit architecture; on this call he answered the questions on the loan book.
“a dear colleague, Kaizad, has requested for early retirement by end of December”— Sashidhar Jagdishan, MD and CEO
Impact 4/5 Guidance Mixed
HDFC Bank says its margin has bottomed and names the October repo rise as a tailwind
An analyst put net interest margin at 3.32%, which the CFO did not dispute; he said the margin is at the bottom without a number and described the outlook as neutral to positive once the full-quarter FCNR cost is netted against the repo rise, and the CEO said it would rise next quarter. That is under the 3.4% to 3.5% band cited in April 2025, if measured the same way (basis not stated on the call). In October 2025 management cited deposit repricing; now it names the 25 basis point October repo rise and retail back-book repricing. Interest expense rose 6.4% from ₹47,626 crore, a second rise in a row.
“The trajectory will be upward from the next quarter onwards.”— Sashidhar Jagdishan, MD and CEO
Impact 3/5 Balance sheet Negative
HDFC Bank's liquidity ratio is about 113%; CFO says a floor near there is needed to grow
An analyst put the liquidity coverage ratio at 113% and the CFO said the bank operates between 110% and 120%, aiming for about 115%; it was 114% in the March 2026 quarter and 116% in December 2025. In the quarter deposits rose ₹1.57 trillion and loans ₹1.58 trillion; the CFO called sources and uses largely matched. Reported year-on-year deposit growth of 18.8% includes about 4 points from the FCNR window. Questions on deposit strategy were passed to the incoming head.
“a low LCR does not mean low liquidity”— Srinivasan Vaidyanathan, CFO
Financials
Income statement, last 8 quarters
| Quarter end | Sales | YoY | Other income | PBT | Net profit |
|---|---|---|---|---|---|
| Sept 2026 | 95,132 | +9.4% | 34,227 | 28,663 | 21,537 |
| Jun 2026 | 90,575 | +3.7% | 42,535 | 27,193 | 20,383 |
| Mar 2026 | 87,182 | +0.5% | 29,737 | 27,672 | 21,074 |
| Dec 2025 | 87,067 | +2.4% | 39,860 | 26,961 | 20,691 |
| Sept 2025 | 86,994 | +4.8% | 31,567 | 26,659 | 20,364 |
| Jun 2025 | 87,372 | +7.1% | 45,683 | 20,850 | 17,090 |
| Mar 2025 | 86,779 | +9.2% | 33,489 | 25,573 | 19,285 |
| Dec 2024 | 85,040 | +9.0% | 27,154 | 23,973 | 18,340 |
Balance sheet
| As of | Equity | Debt | Investments | Fixed assets | CWIP | Total assets |
|---|---|---|---|---|---|---|
| Sept 2026 | 6,03,469 | 5,94,144 | 13,56,850 | 16,431 | 0.0 | 51,65,842 |
| Mar 2026 | 5,86,059 | 5,88,485 | 12,80,216 | 16,492 | 0.0 | 49,07,701 |
| Sept 2025 | 5,39,144 | – | 12,50,391 | 15,538 | 0.0 | 45,14,741 |
| Mar 2025 | 5,21,789 | 6,34,606 | 11,86,473 | 15,258 | 0.0 | 43,92,110 |
Cash flow
| Year end | Operating | Investing | Financing | Free cash flow |
|---|---|---|---|---|
| Mar 2026 | 1,13,506 | 7,477 | −59,005 | 1,10,144 |
| Mar 2025 | 1,27,242 | −3,651 | −1,02,478 | 1,23,267 |
| Mar 2024 | 19,069 | 16,600 | −3,983 | 14,882 |
| Mar 2023 | 20,814 | −2,992 | 23,941 | 17,390 |