HDFC Asset Management Company · HDFCAMC
HDFC AMC's costs fell from the quarter before, but management named no growth rate for what comes next
Costs at HDFC Asset Management dipped from the quarter before after four quarters of growth above 15%, and management gave no rate on the call for what follows the 12% to 15% range it named in October 2025.
Published · Inve Research Desk
HDFC Asset Management Company stock page → More news from 17 Oct 2026
5.8%
cost growth last quarter, before non-cash option charges
Down sharply from 26.8% in the quarter before, and management gave no rate on the call for whether this is the new pace.
How they did last quarter
Operating profit grew faster than revenue because costs dipped, while the cost-growth range management named a year earlier is no longer given.
- Operating profit before option charges₹931 crore, up 16.2% on a year agovs ₹801 crore a year ago, when revenue was ₹1,026 croreProfit grew faster than the 13.9% rise in revenue because costs rose much less.
- Costs before non-cash option charges₹238 crore, 5.8% above a year agovs ₹246 crore in the quarter beforeA fall of 3.3% from the quarter before, calculated from the filed results; management gave no rate on the call for what follows.
- Net profit₹750 crore, up 4.5% on a year agovs ₹718 crore a year ago, which included a ₹46.8 crore income-tax reversalWithout that reversal the rise is about 11.7%, calculated from the reported figures, close to the 11.6% rise in profit before tax.
- Revenue against fund assetsRevenue up 13.9%vs Average mutual fund assets of ₹9.69 trillion, up 10% on a year agoRevenue includes non-fund business, so this is not a fund fee yield.
Costs dipped while profit outgrew revenue
HDFC Asset Management earns a fee on the money it manages for investors, so its profit depends on how fast those fees grow and on what it spends to run the business. In the September 2026 quarter revenue grew 13.9% and operating profit grew 16.2%. Profit outran revenue because costs rose much less than revenue. Costs before non-cash share-option charges, which we calculate as revenue less operating profit, were 5.8% above a year earlier and lower than in the quarter before.
That is a sharp change of pace. In each of the four quarters before, costs grew between 15.9% and 26.8% a year. Management pointed to corporate social responsibility spending booked in the first quarter and asked to be judged on the full year.
Revenue and operating profit, last eight quarters
Operating profit grew faster than revenue in the latest quarter, the gap that restrained costs produced.
₹ crore
| Sales | Operating profit | |
|---|---|---|
| Dec 2024 | 934 | 764 |
| Mar 2025 | 901 | 731 |
| Jun 2025 | 968 | 774 |
| Sept 2025 | 1,026 | 801 |
| Dec 2025 | 1,074 | 877 |
| Mar 2026 | 1,050 | 846 |
| Jun 2026 | 1,098 | 852 |
| Sept 2026 | 1,169 | 931 |
The 12% to 15% cost range from 2025 is no longer restated
In October 2025 the company's chief financial officer, Naozad Sirwalla, said that, on a sustainable basis, 12% to 15% growth in operating expenses was what the company would look at. On our basis, costs grew 16.6% in FY26, a little slower than revenue. Nobody on the call said whether the range included the non-cash option charges, so our figure is not a like-for-like test of it.
By April 2026 the number had been replaced with a statement that costs would broadly grow in line with the business and the investments being made. Asked on the latest call how costs will grow, management again named no rate. Routine costs, it said, move with inflation and business size, while a second group of spending, on a larger alternatives team, international expansion and AI technology, is treated as investment and was not sized. When an analyst asked for a split between the two, the managing director and chief executive, Navneet Munot, said: "We don't split like this is for future and this is for the current business."
One quarter does not show a new run-rate
Management's explanation is plausible, and a single quarter cannot separate cost discipline from timing. Management said first-quarter costs carried corporate social responsibility spending and asked to be judged on the full year. The company also said it will keep adding to its investment spending, so the restraint may not carry forward.
The measure management defends is operating profit per rupee of assets managed, which it put at 36 basis points last quarter, on operating profit of ₹9.1 billion after the non-cash option charges, against ₹931 crore before them in the table used here. A basis point is one hundredth of a percentage point. The cost line that protects that margin is the one it gave no rate for on the call.
Fee income held up, but the flow figure slowed
Revenue grew faster than the 10% rise in average mutual fund assets; revenue includes portfolio management and alternatives business as well as mutual funds, so it is not a fund fee yield. Management attributed the sequential rise in its blended yield mainly to asset mix and said it was not a material movement; it called the rise in equity yield marginal, citing product mix, flows and market moves.
The company's systematic flow figure, which combines SIP (monthly investment plans) and systematic transfers, grew 6% in September from a year earlier, while the industry's SIP-only figure was Rs 325 billion, against Rs 294 billion a year earlier, a rise of 10.5% by our calculation. Management said the two are not like for like and that, with transfers removed, its SIP share had risen; no SIP-only split was given on the call.
HDFC Asset Management Company stock page →
The record: notes, full financial tables
Notes
Impact 4/5 Guidance Mixed
HDFC AMC no longer restates its 12-15% cost range; costs rose 5.8%
On the call management named no growth rate for costs, after naming a 12% to 15% range in October 2025 on a sustainable basis. Nobody on the call said whether the range included the non-cash option charges, which these figures leave out. Costs before non-cash option charges, calculated from the filed results, rose 5.8% in the September 2026 quarter, against 26.8% the quarter before and 16.6% in FY26. By April 2026 the company had already moved to saying costs would broadly track the business, and spending on investments was not sized.
“We don't split like this is for future and this is for the current business.”— Navneet Munot, managing director and chief executive
Impact 4/5 Demand Negative
HDFC AMC's SIP-plus-transfer flow grew 6% in a year, after 24% in December
The company's systematic flow, which combines SIPs and systematic transfer plans, was Rs 48 billion in September 2026, up 6% on a year earlier, after growing 24% to Rs 47.3 billion in December 2025. The industry's SIP-only figure was Rs 325 billion, against Rs 294 billion a year earlier, a rise of 10.5% by our calculation. Management said the two are not like for like, since the company's figure includes transfers and the industry's does not, and that the softness came from slower transfers by wealth managers; it said its SIP-only share had risen, but no split was offered on the call to test that.
“If you strip out STP and look at SIP alone, our market share has actually gone up.”— Navneet Munot, managing director and chief executive
Impact 3/5 Demand Mixed
HDFC AMC says government mandates are highly contested and priced to match
Management said the fixed-income mandate from the EPFO, which began in the September quarter, belongs to a category that is fiercely contested, with pricing to match. Management put fees on its alternative funds at 80 to 90 basis points depending on product, against 58 basis points for overall equity funds; it said discretionary portfolio management earns about what its equity funds do. Asked for a revenue target for alternatives, management said on the call that it does not give guidance of that kind.
“And government mandates like PFO and SPF, they are highly contested and the pricing reflects that.”— Navneet Munot, managing director and chief executive
Impact 2/5 One-off Mixed
HDFC AMC net profit up 4.5%, about 11.7% without last year's tax reversal
Net profit was Rs 750 crore in the September 2026 quarter, up 4.5% from Rs 718 crore. The company said the year-ago figure was helped by a Rs 46.8 crore income-tax reversal. Without it, growth is about 11.7% by our calculation, close to the 11.6% rise in profit before tax. Other income fell to Rs 71 crore from Rs 96 crore a year ago.
“the reported PAT is not directly comparable year-on-year”— Simal Kanuga, HDFC AMC management
Financials
Income statement, last 8 quarters
| Quarter end | Sales | YoY | Operating profit | Op. margin | Other income | PBT | Net profit |
|---|---|---|---|---|---|---|---|
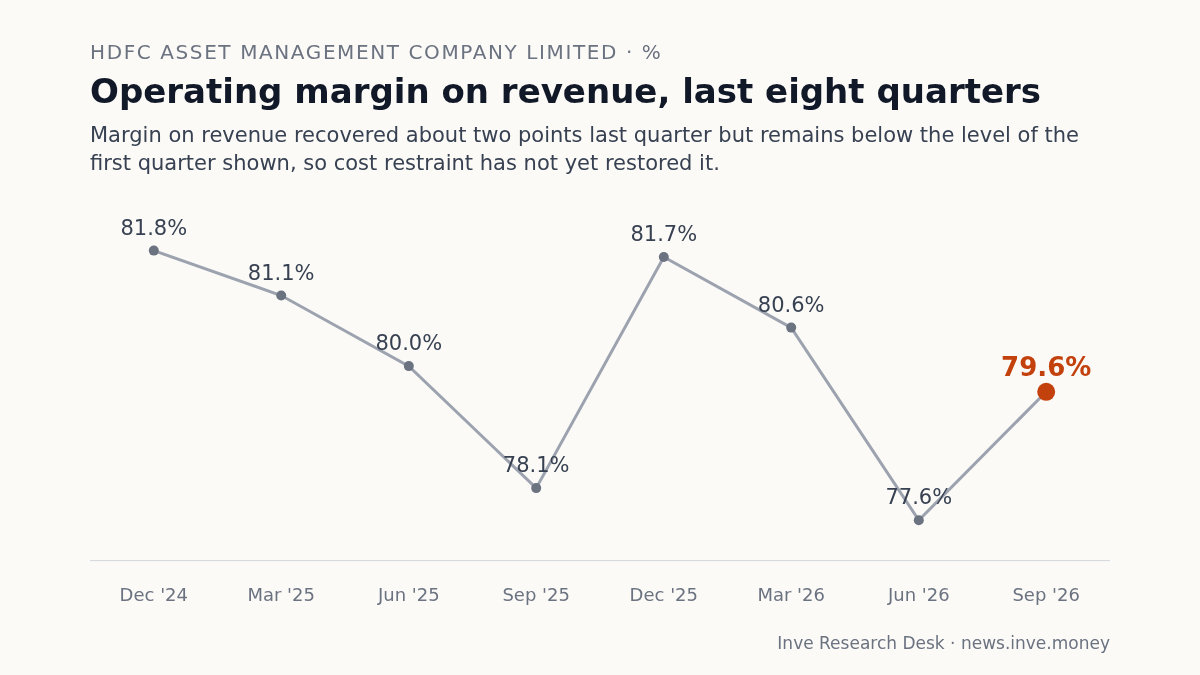
| Sept 2026 | 1,169 | +13.9% | 931 | 79.6% | 71 | 978 | 750 |
| Jun 2026 | 1,098 | +13.4% | 852 | 77.6% | 263 | 1,090 | 838 |
| Mar 2026 | 1,050 | +16.5% | 846 | 80.6% | 11 | 834 | 623 |
| Dec 2025 | 1,074 | +15.0% | 877 | 81.7% | 159 | 1,015 | 770 |
| Sept 2025 | 1,026 | +15.7% | 801 | 78.1% | 96 | 876 | 718 |
| Jun 2025 | 968 | +24.9% | 774 | 80.0% | 233 | 986 | 748 |
| Mar 2025 | 901 | +29.6% | 731 | 81.1% | 124 | 835 | 639 |
| Dec 2024 | 934 | +39.2% | 764 | 81.8% | 93 | 840 | 641 |
Balance sheet
| As of | Equity | Debt | Investments | Fixed assets | CWIP | Total assets |
|---|---|---|---|---|---|---|
| Sept 2026 | 8,623 | 0.0 | 8,746 | 265 | 0.0 | 9,400 |
| Mar 2026 | 9,231 | 0.0 | 9,396 | 268 | 2.0 | 9,988 |
| Sept 2025 | 7,744 | 0.0 | 7,901 | 232 | 0.0 | 8,435 |
| Mar 2025 | 8,134 | 0.0 | 8,289 | 197 | 0.0 | 8,754 |