Axis Bank · AXISBANK
Axis Bank's margin falls to 3.36% and its new CFO drops the timetable for 3.8%
Axis Bank's margin slid below the level management called the bottom in July, while a new finance chief kept the 3.8% target and declined to give a date for reaching it.
Published · Inve Research Desk
3.36%
net interest margin last quarter
Down 10 basis points on the quarter before, which management had called the bottom of the cycle in July; the bank's own adjusted figure is 3.47%.
How they did last quarter
Margin came in lower than management's July reading of the bottom, and reported profit growth looks strong mainly against a depressed year-ago quarter.
- Net interest margin3.36%, 10 basis points lower than the quarter before and 37 lower than a year agovs 3.46% in the quarter before, which management had described as the bottom of the cycleThe reported margin went through the level management named as the floor.
- Net profit7,003 crore, up 37.6% on a year agovs 7,114 crore in the quarter before, a fall of 1.6%The yearly gain rests on a weak base; from the quarter before, profit slipped.
- Net credit cost0.45% of loansvs 0.73% a year agoLower provisioning carried part of the profit gain; the CFO said part of the improvement came from mix, but on the call he did not say which.
- Total assets2,046,240 crore, up 8.4% in six monthsvs 1,886,850 crore at 31 March 2026The balance sheet grew quickly; the bank links part of the growth to the foreign-currency deposit drive.
Margin fell below the level management called the bottom
In the September 2026 quarter Axis Bank's net interest margin, the gap between what it earns on loans and pays on deposits, was 3.36%. In July management had described the quarter before as the bottom of the cycle, so the reported margin has gone through that level.
Calculated from the margins reported on each call, it has fallen quarter on quarter in each of the last six quarters checked.
A deposit drive and thinner spreads
Part of the explanation is a push for FCNR(B) deposits, foreign-currency term deposits from non-resident Indians, where the bank said it won a larger share of the market. Total assets rose 8.4% in six months, and interest earned grew faster than net interest income, what is left after paying for deposits: more earning assets at thinner spreads.
The bank attributes 11 basis points of margin loss to the deposits and puts the margin without that effect at 3.47%. That is the bank's own estimate, and the filed results cannot test it.
Total assets and borrowings, last four balance-sheet dates
Total assets and borrowings both rose in the latest half-year; borrowings rose faster than assets (borrowings are not held for Sep-2025). FCNR(B) deposits sit in deposits, not borrowings, so this does not measure the deposit drive.
₹ crore
| Total assets | Debt | |
|---|---|---|
| Mar 2025 | 16,09,930 | 1,84,147 |
| Sept 2025 | 17,30,109 | – |
| Mar 2026 | 18,86,850 | 2,35,271 |
| Sept 2026 | 20,46,240 | 2,73,086 |
The 3.8% margin target stays and the timetable goes
In October 2025 the bank said margins should bottom out in its fiscal third quarter if no further rate cut came. That call put the 3.8% through-cycle margin at 15 to 18 months out. A further rate cut then followed, calculated from the cumulative cuts the bank cited on its October and January calls, and the margin kept falling. On 25 April 2026 the bank repeated the 15-to-18-month path, counted from the transmission of that last cut. In July management said the 3.8% target, including its time period, was unchanged.
On this call the new chief financial officer, Rajeev Mantri, said the target stays but declined to put a date on it: "from a time line perspective, we won't be able to specifically guide on how much time frame this will take". Asked whether this quarter was the bottom, he answered that the bank had said the previous quarter was "sort of the bottom", pointing to the figure without the FCNR effect. He said the time frame was difficult to ascertain but that, quarter on quarter, the bank should be able to show an improvement going forward. He pointed to improvement from quarter to quarter, with a benefit from deploying the FCNR money in the next two quarters. The gain from the repo-rate rise on the loan book comes a quarter later, because loans reprice in the last week of a quarter.
Profit growth leans on a weak year-ago base
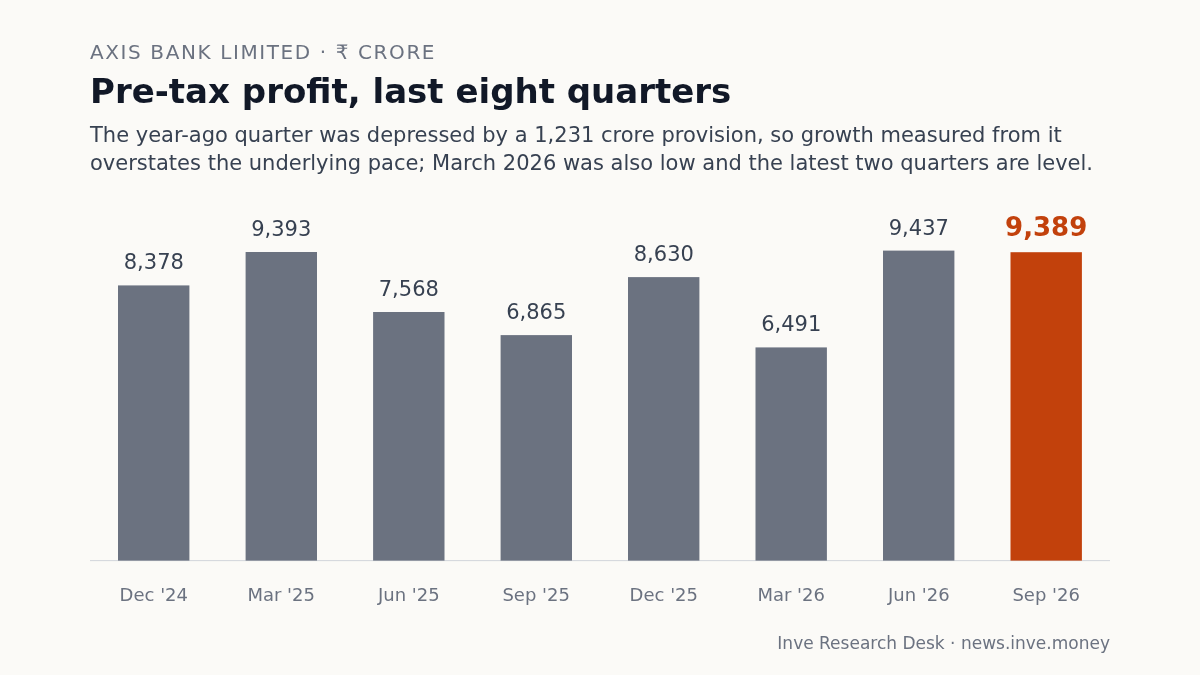
Net profit rose 37.6% on a year ago, but the year-ago quarter carried a one-time provision of 1,231 crore. Adding that back, pre-tax profit grew about 16%, calculated from the reported figures. Against the quarter before, net profit slipped.
Lower credit costs explain part of the profit gain
Net credit cost, the provisions charged against loans, was 0.45% against 0.73% a year ago. The CFO said that "though some portion of this improvement that has come through is also because of the mix". Retail was 54% of loans, unchanged from July. The bank attributes part of the yearly margin fall to a change in balance-sheet mix; on the call, the bank did not say how much of that is loan mix. The two explanations may overlap: on the call, the bank did not say whether the year-ago provision is inside that quarter's credit cost.
The record: notes, full financial tables
Notes
Impact 4/5 Guidance Negative
Axis Bank margin falls to 3.36% as new CFO drops the timetable for 3.8%
CFO Rajeev Mantri said the 3.8% through-cycle margin guidance is unchanged but would not say how long it takes. Net interest margin was 3.36% in the September 2026 quarter, 10 basis points below the 3.46% that management called the bottom of the cycle on 18 July 2026; the bank's figure excluding foreign-currency deposit effects is 3.47%. On 15 October 2025 the bank had said margins should bottom in the third quarter of FY26 if no further rate cut came. A further 25-basis-point cut came before its 26 January 2026 call; on 25 April 2026 it repeated the 15 to 18 month path to 3.8%, counted from that cut's transmission.
“from a time line perspective, we won't be able to specifically guide on how much time frame this will take”— Rajeev Mantri, Group Head and CFO
Impact 3/5 One-off Mixed
Axis Bank's 38% profit rise is 16% pre-tax with a 1,231 crore provision added back
Net profit was 7,003 crore in the September 2026 quarter, up 37.6% on a year ago, but that quarter carried a one-time provision of 1,231 crore. Adding it back to the year-ago pre-tax profit of 6,865 crore, pre-tax profit rose about 16%, calculated from the reported figures; net profit fell 1.6% from 7,114 crore in the quarter before. Net credit cost was 0.45%, against 0.73% a year ago, and the CFO said on the call that part of that improvement came from mix, but did not say which mix. On the call the bank did not say whether the 1,231 crore is inside that 0.73%.
“though some portion of this improvement that has come through is also because of the mix”— Rajeev Mantri, Group Head and CFO
Impact 3/5 Guidance Mixed
Axis Bank's retail share of loans is still 54%, against 58-60% called optimal in January
Retail made up 54% of loans, corporate 34% and small business 12% in the September 2026 quarter, the same split as in July. Wholesale loans grew 34% on a year ago and retail 16% (10% excluding loans made against foreign-currency deposits). On 26 January 2026 the bank put optimal retail at 58 to 60% of the book; on 25 April 2026 it said about 70% retail and small business against 30% wholesale, give or take 3 to 4 points, and the two together are 66% now, at the low edge of that 66 to 74 range. Executive Subrat Mohanty said the bank aims to get back above 55% retail.
“we do not further move away from the mix that we are right now and we get back to the above 55% retail mix”— Subrat Mohanty, Axis Bank executive
Impact 3/5 Balance sheet Mixed
Axis Bank assets up 8.4% in six months; bank puts FCNR deposit margin cost at 11 bps
The bank said it has an 8% share of the market in FCNR(B) deposits, foreign-currency deposits from non-resident Indians, in the September 2026 quarter. Total assets were 2,046,240 crore at 30 September 2026 against 1,886,850 crore at 31 March 2026, and the bank puts the margin cost of the deposits at 11 basis points. The 11 basis points is the bank's estimate for one quarter, and the bank said loans grew 23% on a year ago and 9% on the quarter, or 19% and 5% excluding loans its international branches made against FCNR(B) deposits; it gave no such split for total assets on the call.
“there is runway for the balance sheet to grow given the fact there is an incremental liability that we have raised”— Amitabh Chaudhry, MD and CEO
Impact 3/5 Guidance Mixed
Axis Bank's CFO sees no material impact from expected-credit-loss rules
Asked about provisioning into FY28, Rajeev Mantri said the bank does not expect a material impact from the move to expected-credit-loss rules, and pointed to contingent provisions of 8,006 crore, 49 basis points over reported capital ratios. On 18 July 2026 the bank had said the industry, including itself, should see higher provisions in the first year of the transition; the July statement put no size on the rise and the CFO describes his view as unchanged, so the two statements do not directly contradict each other. Provisions were 8,244 crore at 31 March 2026, so the buffer is 238 crore lower; the call did not explain the change.
“we don't expect any material impact to come through on the transition itself”— Rajeev Mantri, Group Head and CFO
Impact 3/5 Risk Negative
Axis Bank fee growth is 6%, against 12% in December 2025, with a draft insurance rule open
Fees were 6,381 crore in the September 2026 quarter, up 6% on a year ago and 4% on the quarter before; three quarters earlier fees were 6,100 crore, up 12%, and the quarter ended 31 March 2026 was up 4%. Mohanty put the slower growth down to lower asset-linked fees on corporate lending, weak card spending and the festive month shifting from September to October; the draft rule has not yet affected these results. Executive Subrat Mohanty said a draft rule on insurance distribution is at an early stage and the bank expects about 6 to 9 months before it comes through.
“the consultation paper is out, I still think it's early days”— Subrat Mohanty, Axis Bank executive
Financials
Income statement, last 8 quarters
| Quarter end | Sales | YoY | Other income | PBT | Net profit |
|---|---|---|---|---|---|
| Sept 2026 | 36,419 | +17.6% | 6,531 | 9,389 | 7,003 |
| Jun 2026 | 33,986 | +9.4% | 6,735 | 9,437 | 7,114 |
| Mar 2026 | 32,724 | +4.7% | 6,023 | 6,491 | 7,071 |
| Dec 2025 | 32,274 | +4.3% | 6,226 | 8,630 | 6,490 |
| Sept 2025 | 30,970 | +1.8% | 6,625 | 6,865 | 5,090 |
| Jun 2025 | 31,064 | +3.3% | 7,258 | 7,568 | 5,806 |
| Mar 2025 | 31,243 | +6.9% | 6,780 | 9,393 | 7,118 |
| Dec 2024 | 30,954 | +10.7% | 5,972 | 8,378 | 6,304 |
Balance sheet
| As of | Equity | Debt | Investments | Fixed assets | CWIP | Total assets |
|---|---|---|---|---|---|---|
| Sept 2026 | 2,18,750 | 2,73,086 | 4,53,464 | 6,640 | 0 | 20,46,240 |
| Mar 2026 | 2,05,537 | 2,35,271 | 4,45,033 | 6,289 | 260 | 18,86,850 |
| Sept 2025 | 1,98,260 | – | 3,92,986 | 6,620 | 0 | 17,30,109 |
| Mar 2025 | 1,79,725 | 1,84,147 | 3,96,142 | 6,190 | 101 | 16,09,930 |