Conagra Brands · CAG
Conagra cleared a low bar, but its unchanged guide assumes earnings drop from here
Conagra beat its own margin guide by more than two points and held the full-year guide, which by our arithmetic implies the rest of the year earns far less per share.
Published · Inve Research Desk
11.5%
adjusted operating margin last quarter
More than two points above the "high single digits" the company guided in July (we read that as up to 9%), yet the unchanged full-year guide implies roughly 9.5% to 10.2% for the rest of the year by our arithmetic.
How they did last quarter
Better than the company said it would be, on a bar it set below the year's own guide, with weaker cash and a flattered margin underneath.
- Adjusted operating margin11.5%, against 11.8% a year agovs Guide of "in the high single digits" for the quarter (15 July)Cleared by more than two points, though a one-time incentive-pay credit and spending timing added about 0.8 points of it, by our arithmetic.
- Organic net sales-1.1%, with volume -2.1% and price/mix +1.0%vs Guide of "decline low single digits" for the quarter (15 July)Inside the guide; volume fell more than price added, before the frozen price rises.
- Free cash flow-$127.9Mvs -$26.2M a year agoCash drained faster than a year ago.
- Net leverage3.99xvs Year-end guide of "approximately 4x" (15 July)Already at the year-end level after one quarter, which the finance chief called better than planned, with the seasonal rise still ahead.
A low bar, set in July and cleared in September
In July Conagra's new chief executive reset the year, and the finance chief said the next quarter would earn an adjusted operating margin in the high single digits. That is the profit from running the business before items the company strips out. The bar sat below the margin guided for the full year and below the 11.8% of a year earlier. In the August 2026 quarter the company reported 11.5%.
The full-year guide did not move. The chief financial officer said "we thought it was prudent to hold the year, it's 1 quarter, and then we'll update at the half".
The beat was thinner than the headline suggests
Two things flattered the quarter. A one-time credit for last year's incentive pay and some spending that was only a matter of timing sat in overhead; the finance chief put the earnings benefit at half one-time and half timing. Take them out and, by our arithmetic, the margin is nearer 10.7%, only just above the top of the full-year range. That is still clear of the quarter's guide, but the quarter did not run far ahead of the year.
The other help came below the operating line. The Ardent Mills flour joint venture's earnings rose sharply, which lifted earnings per share but not the margin. By our arithmetic only about 36% of them arrived as cash in the quarter, while the finance chief said "in terms of profit, we have a minimum of 80% cash flow conversion on that profit". In the Q&A he did not say over what period that applies, and one quarter's distributions can lag its earnings. He also called the line hard to forecast.
The unchanged guide assumes earnings fall from here
Hold the full-year adjusted earnings guide of $1.40 to $1.50 a share against what is already reported, and the remaining three quarters earn far less than the same three did last year. By our arithmetic that is a fall of about 18% to 26%, or about 15% to 23% if last year's extra week, worth a few cents of the guide, is set aside.
Management named the reasons. Inflation sits toward the high end of its range because transport cost inflation is running at double the planned rate, and the second and third quarters take the worst of it. Marketing spend rises, and the timing half of the overhead favourability reverses. And price increases on frozen food have only just reached shelves. The plan assumes shoppers cut volume by about two percent for each percent of price in frozen, and it assumes no rival matches the price, which the chief executive said would be upside if it happened. He also said early results were in line with the plan. A full quarter of frozen volumes with the new prices has not yet been reported.
Cash and borrowing leave little room for a miss
Free cash flow was negative $127.9M in the quarter, worse than a year earlier. The full-year guide is free cash flow above 90% of adjusted net income, which by our arithmetic needs about $754M over the other three quarters, less than they produced last year. The first quarter is seasonally weak as inventory is built, but free cash flow fell in each of the last two fiscal years shown. This quarter the company paid dividends and bought back shares; separately, it raised a note in July that the finance chief said was to refinance bonds due in October.
Net leverage, which is net debt divided by a year's adjusted earnings before interest, tax, depreciation and amortization, reached 3.99x after one quarter, already at the year-end guide. The finance chief called that better than planned. By our arithmetic, if those trailing earnings were 5% lower with net debt unchanged, the ratio would be about 4.2x, a sensitivity and not a forecast. Debt is lower than a year earlier, but equity fell by more after large impairment charges, so debt now weighs more against equity.
Free cash flow by fiscal year
Free cash flow fell in the last two fiscal years, so the plan to pay down debt starts from a smaller cash base.
Free cash flow, $ million
- May 2023 633
- May 2024 1,628
- May 2025 1,303
- May 2026 979
Debt and equity, last four balance sheets
Equity dropped sharply with impairment charges while debt barely moved, so borrowing now weighs more against what owners hold.
$ million
| Debt | Equity | |
|---|---|---|
| Nov 2025 | 7,628 | 8,091 |
| Feb 2026 | 7,328 | 8,164 |
| May 2026 | 7,234 | 6,358 |
| Aug 2026 | 7,763 | 6,405 |
What we do not know, and when we will
We do not know whether the guide is conservative or realistic. The half-year update, with the next quarter's results, will show whether the margin lands near the guided high single digits, and whether frozen volumes behave as assumed.
The record on bars is mixed. The July margin bar was cleared and the sales bar was met. In April, before the change of chief executive, the finance chief said he did expect positive organic net sales growth for the fourth quarter; the July call reported the quarter flat. Holding a guide after one good quarter is what a cautious management does, and also what one expecting a weaker second quarter does. The finance chief called it prudent, and the half-year update is when that stops being a matter of reading.
The record: notes, full financial tables
Notes
Impact 4/5 Guidance Mixed
Conagra holds FY27 guide after 11.5% adjusted margin; rest of year implies a step down
Management kept its fiscal 2027 guide for organic net sales, adjusted operating margin and adjusted EPS after a quarter whose adjusted operating margin ran above its own guide. Adjusted operating margin was 11.5% in the August 2026 quarter, against "high single digits" guided on 15 July. The full-year adjusted guide of 10.0% to 10.5% implies roughly 9.5% to 10.2% for the other three quarters, by our arithmetic, with a second-quarter guide of organic sales down 2%. The company said it would update at the half.
“we thought it was prudent to hold the year, it's 1 quarter, and then we'll update at the half”— David Marberger, chief financial officer
Impact 4/5 Balance sheet Negative
Conagra burned $127.9M of free cash; leverage at 3.99x, near the roughly 4x guide
Free cash flow was negative $127.9M in the August 2026 quarter, against negative $26.2M a year earlier, and net leverage reached 3.99x, which the finance chief called favorable to plan. In July the company guided to about 4x at year end and a free-cash-flow conversion target above 90%. He said leverage usually rises in the first half on seasonal inventory and put debt paydown at about $250 million for the year, toward a 3x long-term target. By our arithmetic, 5% lower trailing adjusted EBITDA, with net debt unchanged, would take leverage to about 4.20x.
“We are maniacally focused on getting there as soon as possible.”— David Marberger, chief financial officer
Impact 4/5 Demand Mixed
Conagra's guide assumes frozen volumes fall about 2:1 against price, and no rival follows
The chief executive said July's price increases are only now reaching shelves and that early pricing results are in line with the plan. As he described it, the plan models about two percent of volume lost per percent of price in frozen and about one in grocery and snacks, with no rival following; if rivals did follow, that would be upside. Organic net sales fell 1.1% in the August 2026 quarter, with volume down 2.1%, before the new frozen pricing. Management guided the next quarter to a 2% organic decline, after guiding volumes down mid-single digits for the year in July.
“we have not assumed any followership our pricing moves”— John Brase, chief executive
Impact 3/5 Margin Negative
Conagra sees FY27 inflation near top of 5%-6% as transport inflation runs at double plan
The finance chief placed inflation toward the high end of a 5% to 6% range because transport cost inflation is running at double the planned rate, partly offset by cheaper proteins. An analyst put August-quarter inflation near the low end of the range and the finance chief did not dispute it, so the pressure is mostly ahead, with the second and third quarters expected to be heavier. Gross margin was 23.8% in that quarter, against 24.3% a year earlier. It still guides full-year gross margin roughly flat on the prior year, and the operating-margin guide is unchanged from 15 July.
“the doubling of inflation in transportation versus where we planned it for the year”— David Marberger, chief financial officer
Impact 3/5 One-off Mixed
Ardent Mills earnings rose 72% to $50.4M, but about 36% came back as cash
Equity earnings from the Ardent Mills flour joint venture were $50.4M in the August 2026 quarter, up from $29.4M a year earlier; the line sits below operating profit, so it lifts earnings per share, not the adjusted operating margin. By our arithmetic about $18.2M, or 36%, arrived as cash, against 99% a year earlier. The finance chief said the profit carries a minimum 80% cash conversion and called it hard to forecast, but in the Q&A gave no period, and one quarter's distributions can lag its earnings. He held the full-year guide of about $140M, which this quarter's $50.4M already covers more than a third of.
“in terms of profit, we have a minimum of 80% cash flow conversion on that profit”— David Marberger, chief financial officer
Impact 2/5 Margin Positive
Conagra exits Celeste pizza, works to simplify 400-plus meals; benefit mostly FY28
The chief executive said a work stream is cutting product lines, starting with small low-profit brands such as Celeste pizza and moving to core platforms, with over 400 single-serve meal products as the example of a range that could become much simpler. In the Q&A and the release, no savings figure or FY27 benefit was given; the benefit is said to come mainly in fiscal 2028.
Financials
Income statement, last 8 quarters
| Quarter end | Sales | YoY | Operating profit | Op. margin | PBT | Net profit |
|---|---|---|---|---|---|---|
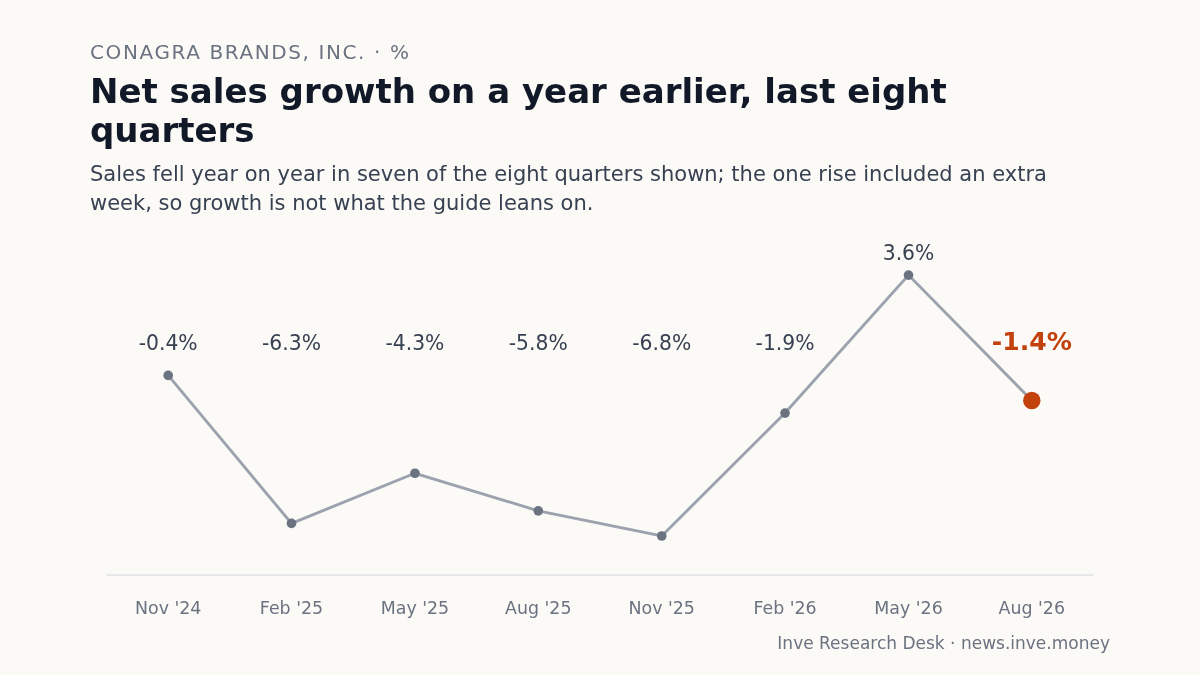
| Aug 2026 | 2,596 | −1.4% | 268 | 10.3% | 233 | 174 |
| May 2026 | 2,882 | +3.6% | −1,658 | −57.5% | −1,688 | −1,617 |
| Feb 2026 | 2,788 | −1.9% | 280 | 10.0% | 230 | 200 |
| Nov 2025 | 2,979 | −6.8% | −598 | −20.1% | −655 | −664 |
| Aug 2025 | 2,633 | −5.8% | 347 | 13.2% | 289 | 165 |
| May 2025 | 2,782 | −4.3% | 3 | 0.1% | 293 | 256 |
| Feb 2025 | 2,841 | −6.3% | 239 | 8.4% | 189 | 145 |
| Nov 2024 | 3,195 | −0.4% | 403 | 12.6% | 346 | 285 |
Balance sheet
| As of | Equity | Debt | Cash | Fixed assets | Total assets |
|---|---|---|---|---|---|
| Aug 2026 | 6,405 | 7,763 | 372 | 2,824 | 17,702 |
| May 2026 | 6,358 | 7,234 | 218 | 2,863 | 17,274 |
| Feb 2026 | 8,164 | 7,328 | 55 | 2,801 | 19,212 |
| Nov 2025 | 8,091 | 7,628 | 47 | 2,802 | 19,540 |
Cash flow
| Year end | Operating | Investing | Financing | Free cash flow |
|---|---|---|---|---|
| May 2026 | 1,402 | 263 | −1,516 | 979 |
| May 2025 | 1,692 | −542 | −1,158 | 1,303 |
| May 2024 | 2,016 | −375 | −1,657 | 1,628 |
| May 2023 | 995 | −355 | −632 | 633 |