
McCormick & Company, Incorporated · MKC
A strong operating quarter left McCormick's full-year earnings guidance unchanged, so Q4 earnings per share must fall
McCormick beat its operating-income guide but held full-year earnings guidance, which by our arithmetic leaves a weaker fourth quarter, while the volume recovery it guided in June has been softened.
Published · Updated · Inve Research Desk
McCormick & Company, Incorporated stock page → More news from Oct 1, 2026
$0.77
implied Q4 adjusted EPS at midpoint, by our arithmetic
About 10% below the $0.86 of adjusted EPS reported for the same quarter a year earlier (22 Jan 2026 release): the quarter just reported did not change the earnings guide for the year, part of it was drawn from the quarter still to come.
How they did last quarter
Operating income beat June's guide; per-share earnings rose only 1.2%, with SG&A and a tax comparison weighing as June had said; volume improved as guided in the third quarter yet still fell; fourth-quarter growth softened.
- Adjusted operating income$358.5 million, +22.1% on a year agovs Guidance of 25 June 2026: Q3 adjusted operating income to grow "high single to low double digits"Well ahead of the guide, though the finance chief said some expenses moved into the fourth quarter.
- Adjusted EPS$0.86, +1.2%vs $0.85 a year agoThe operating gain was absorbed by a 22.6% adjusted tax rate against 16.1%, higher interest and the minority share.
- Consumer Americas volume and mix-2.5%, with price +2.2%vs -3.6% the quarter before, and the 25 June guidance of "sequential volume improvement in the third quarter and volume growth in the fourth quarter"Better than the 3.6% fall the quarter before, still a decline. The third-quarter guide of improvement was met; the fourth-quarter growth guide is now continued improvement.
- Operating cash flow$168.1 millionvs $258.8 million a year agoAbout a third lower by our arithmetic, in the quarter before the Unilever financing.
A big operating quarter that did not move the year
In the August 2026 quarter McCormick's adjusted operating income rose 22.1%, well ahead of the growth it had guided in June. A holder waiting for a raised year would have expected the guidance to move. It did not: adjusted earnings per share guidance for the year was reaffirmed.
A company that beats its own guide by a wide margin and changes nothing has either left itself room or moved cost into the next quarter, and the finance chief pointed to timing. He said "there are timing of expenses that shifted from Q3 into Q4" and gave no figure on the call for the amount that shifted; he added that some productivity savings had been pulled forward. Nine months of adjusted EPS leaves the fourth quarter with $0.77 at the midpoint of the guide, by our arithmetic. That is about 10% below the $0.86 of adjusted EPS reported for the same quarter a year earlier (22 Jan 2026 release).
Operating profit rose; per-share earnings barely moved
Adjusted EPS was $0.86 against $0.85 a year ago. The gap to the operating gain is a higher tax rate, higher interest, and a minority share of the business McCormick took control of in January. Income from unconsolidated operations also fell, to $3.0M from $19.1M.
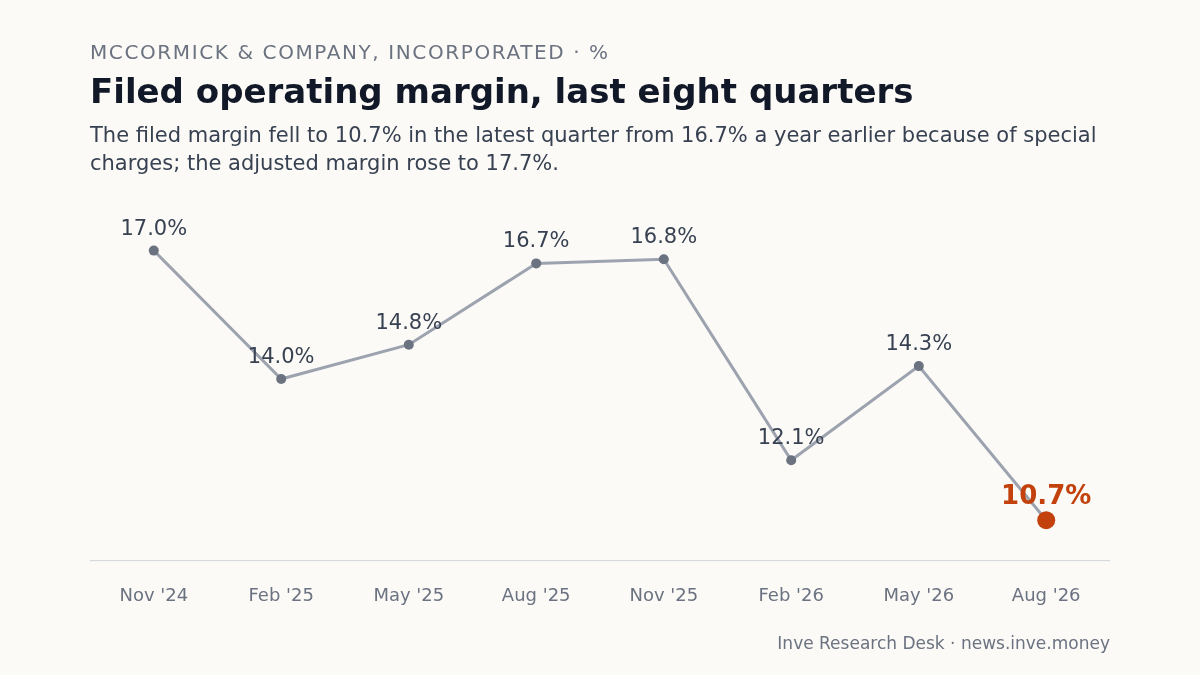
On the filed basis the quarter looks worse: the operating margin was far lower than a year ago, as the first exhibit shows. The difference is special charges, including deal costs and a non-cash write-down on a Malaysia pepper-sourcing project. Adjusted, the margin rose.
Sales grew on the acquisition; the volume recovery softened
Sales rose 17.4%, but most of that came from the acquisition, and organic growth was all price. In Consumer Americas volume and mix fell 2.5%, a smaller decline than the 3.6% fall the quarter before.
In June the company guided to consumer volume improvement in the third quarter (sequential) and consumer volume growth in the fourth. This month the words became continued improvement, with a packaging supply constraint that could take up to one point off fourth-quarter volume. The finance chief said a formal outlook for next year is too early but expects inflation to continue and more pressure on margins and EPS.
Sales growth on a year earlier, last eight quarters
Growth jumped from low single digits to about 17% when the acquired business was consolidated in January 2026; organic growth was only 1.9%.
Sales YoY, %
- Nov '24 +2.6%
- Feb '25 +0.2%
- May '25 +1.0%
- Aug '25 +2.7%
- Nov '25 +2.9%
- Feb '26 +16.7%
- May '26 +16.7%
- Aug '26 +17.4%
Borrowings are higher before the Unilever financing
Total borrowings rose 25.6% in nine months. Most of the rise came with the January purchase of the Mexican business, 729.9 million in cash paid in the nine months; since the end of May, the quarter-end before the company said on 25 June that it would continue to make progress paying down debt, borrowings have gone up by 84.7 million, not down; it repeated the aim on 1 October while the company's own leverage measure held at about 2.9, unchanged from June.
Total borrowings and cash, last four quarters
Total borrowings, short-term plus long-term, rose about a quarter in nine months, most of it with the January purchase of the Mexican business, while cash rose by far less, so the Unilever financing starts from a higher base.
$ million
| Debt | Cash | |
|---|---|---|
| Nov 2025 | 3,996 | 96 |
| Feb 2026 | 4,923 | 178 |
| May 2026 | 4,934 | 331 |
| Aug 2026 | 5,018 | 331 |
Unilever: the September date was kept; January is next
In June McCormick said it would share more detail by the end of September on the operating model, synergies, growth plans and transition services. It announced the operating model and leadership in July, and at a Barclays conference on 9 September it set out its growth priorities, where the cost synergies would come from, and a phased exit from the transition services. On 1 October the finance chief said the more detailed plan for leaving those services would come in the next few months, hopefully by the January results.
The year's earnings guidance held, while the volume turn softened. What we do not know yet is whether the fourth quarter lands inside the range the guide implies, and what the first outlook for next year says. On the September Unilever Foods disclosure McCormick did what it said it would, and it left the full-year adjusted earnings guidance alone; the return of volume is now expected more gradually than guided. A company that holds the year steady after a big quarter puts the strain on the quarter still to come, and the first place a holder sees it is the fourth-quarter print and the first outlook for next year.
McCormick & Company, Incorporated stock page →
The record: notes, full financial tables
Notes
Impact 4/5 Guidance Negative
McCormick holds FY26 EPS guide after a beat, leaving about $0.77 for Q4
Management reaffirmed fiscal 2026 adjusted EPS guidance of $3.05 to $3.13 after adjusted operating income rose 22.1% in the August 2026 quarter. Nine-month adjusted EPS was $2.32, so by our arithmetic the fourth quarter is left with $0.73 to $0.81, about 10% at the midpoint below the $0.86 of adjusted EPS reported for the same quarter a year earlier (22 Jan 2026 release). On 25 June the company had guided the third quarter's adjusted operating income to grow high single to low double digits.
“there are timing of expenses that shifted from Q3 into Q4”— Marcos Gabriel, chief financial officer
Impact 4/5 Guidance Negative
McCormick flags more pressure on FY27 margins and EPS; no formal outlook yet
Asked whether cost pressure will last, the finance chief said inflation should continue into next year (his words were "as we go into 2026", speaking about fiscal 2027) and the productivity program would continue too, but he sees more headwinds for margins and earnings per share. FY26 cost inflation is now guided at 6% to 7%, against a mid-single-digit guide on 25 June, then tracking about 6%, and the gross margin gain of 1.0 to 1.2 percentage points is at the high end, with about 0.35 points from tariff refunds, by the finance chief's figure. The CEO said US pricing will not go negative but may add less than this year.
“it's a little bit too early to talk about a formal outlook for 2027”— Marcos Gabriel, chief financial officer
Impact 3/5 Demand Negative
McCormick Q3 volume fell 0.3% while price added 2.2%; the Q4 volume guidance softened
Total volume and mix fell 0.3% and price rose 2.2%, so organic growth of 1.9% was all price; Consumer Americas volume fell 2.5%, a smaller decline than the 3.6% fall in the previous quarter. On 25 June the company guided to consumer volume growth in the fourth quarter; on 1 October it spoke of continued improvement and a packaging supply constraint that could cut up to one point from fourth-quarter total company volume growth. The June guide of sequential improvement in the third quarter was met in Consumer Americas. The CEO called it a short-term industry issue.
“we are managing a short-term industry supply constraint on a specific type of packaging material”— Brendan Foley, chief executive officer
Impact 3/5 Margin Mixed
McCormick adjusted operating income up 22.1%, adjusted EPS up only 1.2%
Adjusted operating income was $358.5 million against $293.6 million a year ago, yet adjusted EPS was $0.86 against $0.85, held back by a 22.6% adjusted tax rate against 16.1%, higher interest and the minority share of the acquired business. GAAP EPS was $0.36 against $0.84 after $141.5 million of special charges, including a $43.1 million non-cash write-down on a Malaysia pepper-sourcing project. On 25 June the company said it expected to lap a favorable tax rate.
Impact 3/5 Guidance Mixed
McCormick met its Unilever Foods September date; services-exit plan due in months
On 25 June McCormick said it would share more on the Unilever Foods operating model, cost synergies, growth plans and transition services by the end of September; it announced the operating model in July and set out growth priorities, the synergy split and a two-year transition-services exit on 9 September. On 1 October its chief financial officer said a more detailed plan for leaving the transition services would come in the next few months, hopefully by the January results.
“more details to come in the next, I would say, few months”— Marcos Gabriel, chief financial officer
Impact 3/5 Balance sheet Mixed
McCormick Q3 operating cash flow fell to $168.1M while borrowings rose to $5,018.2M
Operating cash flow was $168.1 million in the August 2026 quarter against $258.8 million a year earlier. Total borrowings were $5,018.2 million, up from $3,996.3 million in November 2025, with 42.1% due within a year against 22.3% then. Most of the rise came with the January purchase of the Mexican business (729.9 million paid in the nine months); since May, borrowings are up 84.7 million, while the company said on 25 June, and again on 1 October, that it would continue to make progress paying down debt ahead of the Unilever Foods close. On the company's own measure, leverage was unchanged from June at about 2.9.
“We continue to expect strong performance in our cash flow from operations for the fiscal year”— Marcos Gabriel, chief financial officer
Financials
Income statement, last 8 quarters
| Quarter end | Sales | YoY | Operating profit | Op. margin | PBT | Net profit |
|---|---|---|---|---|---|---|
| Aug 2026 | 2,025 | +17.4% | 217 | 10.7% | 155 | 98 |
| May 2026 | 1,937 | +16.7% | 276 | 14.3% | 220 | 150 |
| Feb 2026 | 1,874 | +16.7% | 228 | 12.1% | 185 | 1,016 |
| Nov 2025 | 1,850 | +2.9% | 311 | 16.8% | 274 | 227 |
| Aug 2025 | 1,725 | +2.7% | 289 | 16.7% | 248 | 226 |
| May 2025 | 1,660 | +1.0% | 246 | 14.8% | 205 | 175 |
| Feb 2025 | 1,606 | +0.2% | 225 | 14.0% | 187 | 162 |
| Nov 2024 | 1,798 | +2.6% | 306 | 17.0% | 264 | 215 |
Balance sheet
| As of | Equity | Debt | Cash | Fixed assets | Total assets |
|---|---|---|---|---|---|
| Aug 2026 | 7,003 | 5,018 | 331 | 1,538 | 16,651 |
| May 2026 | 6,996 | 4,934 | 331 | 1,504 | 16,477 |
| Feb 2026 | 6,980 | 4,923 | 178 | 1,510 | 16,346 |
| Nov 2025 | 5,737 | 3,996 | 96 | 1,449 | 13,200 |
Cash flow
| Year end | Operating | Investing | Financing | Free cash flow |
|---|---|---|---|---|
| Nov 2025 | 962 | −255 | −841 | 740 |
| Nov 2024 | 922 | −269 | −583 | 647 |
| Nov 2023 | 1,237 | −261 | −1,184 | 973 |
| Nov 2022 | 652 | −146 | −487 | 390 |